Enrolled Agent Part 1
study guide
Every chapter of the course summarized, with each section linked to its lesson.
Pass the first time
Try Achievable IRS EA Part 1
No credit card required
This free Enrolled Agent Part 1 study guide summarizes all 8 chapters of Achievable's Enrolled Agent Part 1 course: what each covers, the points to remember, and its 21 sections in order. Read each chapter after you study it, or work through the whole guide before exam day.
Each section links to its full lesson in Achievable, with the review quizzes and full-length practice exams.
Chapter 1: Preliminary work to prepare tax returns
3 sections
Free chapter
- Taxpayer identity checks: Biographical information, prior year returns, immigration status, digital assets, Marketplace insurance questions, and residency tests help verify identity, filing requirements, and whether worldwide income rules apply.
- Return preparation essentials: Filing status, dependents, gross income, deductions, credits, deadlines, signatures, and prior IRS correspondence determine whether a return is required and how it is completed and signed.
- Dependent and child rules: Qualifying child and qualifying relative tests control dependency claims, while income limits, filing thresholds, Form 8814, Form 8615, and kiddie tax rules determine a dependent's filing and tax treatment.
In this chapter
Start this chapter free
Chapter 2: Taxability of income
2 sections
Free chapter
- Worldwide income rule: U.S. citizens are taxed on all worldwide income unless excluded or exempt under IRC §61, using constructive receipt for cash or the all events test for accrual.
- Compensation and investment income: W-2 wages, tips, bonuses, fringe benefits, stock options, interest, dividends, and securities gains are taxable, while exclusions, combat pay rules, and some municipal or exempt-interest amounts are not.
- Business and other items: Self-employment, 1099-K, 1099-NEC/MISC, statutory employee, clergy, hobby, gambling, cancellation of debt, foreign earned income, and adjustments to income all follow specific reporting and deduction rules.
In this chapter
Start this chapter free
Chapter 3: Retirement, investment, and supplemental income
3 sections
- Social security and retirement: Taxability depends on combined income + filing status, and retirement plan distributions are generally taxable except for basis or qualified Roth rules.
- RMDs and plan rules: Mandatory withdrawals start at age 73 or age 75, missed RMDs can trigger a 25% excise tax, and prohibited transactions or improper loans can cause taxable consequences.
- Sales and special income: Capital gains, installment sales, rentals, royalties, K-1 items, PTPs, and digital assets follow special reporting and basis rules that determine ordinary, capital, passive, or tax-free treatment.
Study this chapter in Achievable
Chapter 4: Deductions
3 sections
- Itemized deduction rules: Traditional IRA contribution deduction is an adjustment to income, not a Schedule A item, while excess IRA contributions face a 6% excise tax per year on Form 5329.
- Schedule A limits: Medical expenses exceed 7.5% of AGI, SALT and mortgage interest have caps, charitable donations require substantiation, and casualty losses need a federally declared disaster.
- Business deduction rules: Accounting methods control timing, business expenses must be ordinary and necessary, and special deductions include QBI, depreciation, NOLs, self-employed health insurance, and car loan interest.
Study this chapter in Achievable
Achievable IRS EA Part 1
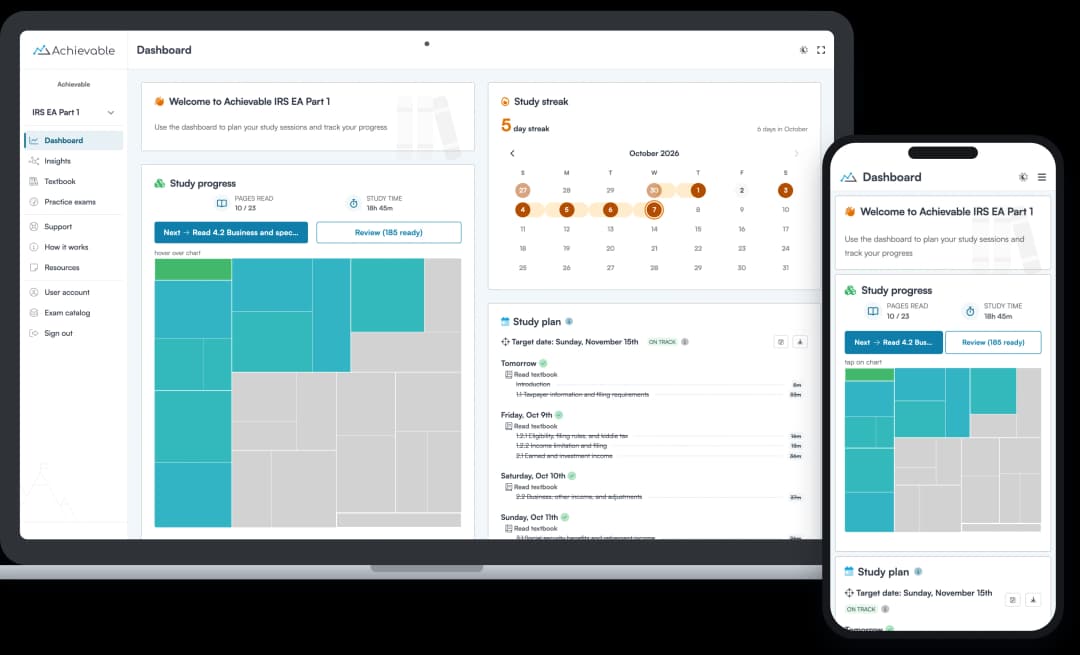
The IRS Special Enrollment Examination (SEE) Part 1 covers individual taxation topics for aspiring Enrolled Agents. Achievable's interactive online EA prep course simplifies complex tax concepts with guided lessons and adaptive practice.
3 full-length practice exams, unlimited retakes
860+ practice questions with explanations
Pass guaranteed, or your money back
Adaptive study plan and exam readiness score
Chapter 5: Credits
3 sections
- Family tax credits: Child and dependent care credit is nonrefundable, child credit is $2,200 per qualifying child under 17, and other dependent credit is up to $500 for dependents not eligible for Child Tax Credit.
- Earned income credit: EITC is refundable for low-to-moderate earned income taxpayers, uses up to 3 qualifying children, and has separate rules for taxpayers with children and taxpayers without children.
- Other credits: Education credits, energy credits, premium tax credit, savers' credit, adoption credit, credit for the elderly and the disabled, foreign tax credits, and fuels credit each have specific forms, limits, and eligibility rules.
Study this chapter in Achievable
Chapter 6: Taxation
2 sections
- Alternative taxes: AMT is a parallel tax system with rates 26%/28%; the taxpayer owes the higher of regular tax or AMT, and NIIT is 3.8% on the lesser of NII or MAGI over threshold.
- Estimated and retirement taxes: Estimated tax avoids penalty by paying 90% of current year tax or safe harbor amount, and premature retirement distributions before age 59½ generally face a 10% additional tax on the taxable portion.
- Credits and deductions: Injured spouse, innocent spouse, FUTA, SE tax, additional Medicare tax, uncollected Social Security and Medicare tax, excess Social Security withholding credit, amended returns, and Schedule 1 versus Schedule 1-A follow their specific filing rules and thresholds.
Study this chapter in Achievable
Chapter 7: Advising the individual taxpayer
2 sections
- Divorce filing rules: Filing status is fixed as of Dec 31; divorced or legally separated taxpayers file single, while still-married taxpayers file jointly or separately unless considered unmarried for head of household.
- Reporting and home sale rules: All income is reportable, and sale of home gain may be excluded under §121 or deferred under §1031, while taxable gain is reported on Form 8949/Schedule D.
- Education and planning moves: Coverdell ESAs and §529 plans offer tax-advantaged education savings, and retirement, estate, gifts, trusts, and charitable giving rules control deductions, rollovers, and taxable treatment.
Study this chapter in Achievable
Chapter 8: Specialized returns
3 sections
- Estate transfer rules: Federal tax on transfer of decedent's property at death uses fair market value, and gross estate includes property, life insurance, and retirement balances under the stated rules.
- Return deductions and elections: Form 706 and Form 1041 have separate filing rules, deductions, deadlines, and elections, including alternate valuation, marital deduction, DSUE portability, and GST tax treatment.
- Gifts and foreign reporting: Gift tax, unified credit, and life insurance proceeds follow the stated exclusion rules, while FBAR, Form 8938, and other international information returns have separate filing thresholds and penalties.
Study this chapter in Achievable
Enrolled Agent Part 1 exam at a glance
- Questions
- 100 multiple-choice questions (85 scored, 15 experimental)
- Time
- 3.5 hours
- Passing score
- 500 (on a scale of 200-800)
- Exam fee
- $317 per part
More on the Enrolled Agent Part 1 exam
- Enrolled Agent Part 1 exam prep courseAchievable's course: online textbook, review quizzes and full-length practice exams.
- Enrolled Agent Part 1 exam format, content and scoringWhat's tested, how long it takes, what it costs, and the score you need to pass.
- Free Enrolled Agent Part 1 practice examPractice questions written to match the real thing, with an explanation for every answer.
- Enrolled Agent Part 1 FAQThe questions asked most about the exam and preparing for it, answered.
- Best Enrolled Agent Part 1 exam prep coursesHow the leading providers compare on content, format and price.
- Enrolled Agent Part 1 study resourcesGuides and study advice from Achievable's instructors.
Pass the IRS EA Part 1. Guaranteed.
Achievable is the best IRS EA Part 1 prep course: effective, personalized, and convenient. With Achievable, you'll spend less time studying and pass your exam the first time, or your money back.