Achievable logo

Life and Health Insurance practice exam
Take Achievable's free Life and Health Insurance practice exam with 95 questions and detailed explanations.
Take free Life and Health Insurance practice exam
Achievable white logo on blue background
Achievable blue logo on white background

Free Life and Health Insurance practice exam

Before you begin
95 questions2 hr time limit100% free

This free Life and Health Insurance practice exam simulates the actual test experience to help you prepare for exam day. Questions are designed to match the real Life and Health Insurance exam format, difficulty, and time constraints. Once you select an answer, it's locked in. Your progress is saved automatically, so you can return anytime. Good luck!

Solve each of the Life and Health Insurance practice test questions below to get a feel for what to expect on the actual Life and Health Insurance exam. Achievable's free Life and Health Insurance practice questions are scored instantly, providing the correct answer along with an easy to understand explanation. Get started on the path to passing the Life and Health Insurance exam by solving 95 Life and Health Insurance exam sample questions.
Question 1

Which of the following situations BEST illustrates the principle of indemnity?

A.
An insured intentionally damages property to collect an insurance payout.
B.
An insured receives reimbursement that restores them to their pre-loss financial position.
C.
An insured receives more money from the insurer than the actual amount of the loss.
D.
An insured takes out multiple life insurance policies as an investment strategy.
Question 2

Joanna pays $50 a month for insurance coverage but receives $50,000 after a major surgery. What feature of her insurance contract does this best illustrate?

A.
Balanced premium-to-benefit ratio
B.
The outcome is based on chance, and consideration may not be equal.
C.
Predictable contributions and benefits
D.
Equal exchange of value
Question 3

Julia buys a disability income policy so that a large uncertain loss is replaced by a small certain premium. Which method of managing risk is she using?

A.
Retention
B.
Transfer
C.
Reduction
D.
Sharing
Question 4

Olivia sells her car to eliminate the risk of accidents and costly repairs. Which risk management method is she demonstrating?

A.
Retention
B.
Sharing
C.
Avoidance
D.
Transfer
Question 5

An insurer relies on statistics from thousands of policies to guide its pricing and reserve decisions. What does this allow the company to do?

A.
It eliminates all risk for the company
B.
It predicts exactly who will file a claim
C.
It guarantees every insurer will be profitable
D.
It helps predict losses with reasonable accuracy
Question 6

Sarah buys renters insurance so she won’t have to pay out of pocket if her apartment is burglarized. She says the small monthly premium is worth it. What is Sarah doing when she buys the policy?

A.
Retaining the risk and paying out-of-pocket
B.
Avoiding risk by leaving the apartment
C.
Transferring the financial burden to the insurer
D.
Buying more coverage to take on more risk
Question 7

Daniel receives a check labeled policy dividends from his insurance provider, which is owned by its policyholders. What kind of company is this?

A.
A stockholder-owned insurance company
B.
A mutual insurance company that shares earnings with policyholders
C.
A company that only issues non-participating policies
D.
A company not subject to state regulation
Question 8

A group of contractors forms an agreement to cover each other’s liability losses by setting up individual accounts that fund claims. The arrangement is managed by a single administrator. What type of insurer is this?

A.
A stock company
B.
A mutual company
C.
A fraternal organization
D.
A reciprocal insurer
Question 9

Which statement best describes the McCarran-Ferguson Act of 1945?

A.
It affirms state regulation of insurance except where federal law provides otherwise
B.
It gave the federal government primary control over insurance regulation
C.
It exempted insurers from state solvency requirements
D.
It required all insurers to be organized as mutual companies
Question 10

After a series of hurricanes causes major claims, a regional insurer avoids collapse because another company had agreed in advance to take on a portion of those losses. What arrangement did the first insurer use to protect itself?

A.
Subrogation
B.
Excess and surplus coverage
C.
A joint underwriting association
D.
Reinsurance
Question 11

James is an agent whose contract doesn’t mention ordering medical exams for applicants, but he regularly does it to help process applications. The insurer accepts this and allows it. What type of authority is James using in this case?

A.
Implied authority
B.
Express authority
C.
Apparent authority
D.
Inherent authority
Question 12

Ben signs a contract with an insurer that lists the duties he’s allowed to perform, including collecting premiums, delivering policies, and submitting applications. What type of authority is granted in this contract?

A.
Apparent authority
B.
Implied authority
C.
Express authority
D.
Fiduciary authority
Question 13

Emily applies for auto insurance and sends in her completed application with the first premium. A few days later, the insurer sends her a policy with the coverage terms. In this situation, which part represents the acceptance?

A.
When Emily fills out the application
B.
When she agrees to shop with that insurer again
C.
When the insurer issues the policy
D.
When she talks to the agent about possible discounts
Question 14

Michael intentionally lies on his life or health insurance application about his smoking habits to get a lower premium. He marks himself as a non-smoker even though he smokes daily. What is this kind of action considered in insurance terms?

A.
A misrepresentation
B.
A warranty
C.
Fraud
D.
Implied authority
Question 15

Ben applies for a health insurance policy but doesn’t provide the initial premium. Two weeks later, he’s ready to pay. The insurer asks for a signed update on his current condition. What is this extra document called?

A.
Statement of continued good health
B.
Secondary application
C.
Health insurance ID card
D.
Policy summary
Question 16

Evan, a producer, periodically reviews his clients’ policies to ensure coverage still fits their changing needs. Which duty is he fulfilling?

A.
Policy delivery requirement
B.
Fiduciary responsibility
C.
Replacement regulation
D.
Contract of adhesion
Question 17

Julia is an insurance producer advising a client on coverage. She takes time to understand their financial needs and explains all policy terms clearly. What standard of conduct is Julia following by acting this way?

A.
The commission-based suitability rule
B.
The prudent person rule
C.
The agency disclosure rule
D.
The competitive market rule
Question 18

Which of the following statements about binding and conditional receipts is NOT true?

A.
A conditional receipt provides coverage only if the applicant is found insurable.
B.
A conditional receipt guarantees coverage regardless of insurability.
C.
A binding receipt obligates the insurer to cover the applicant even if death occurs before underwriting is complete, as long as no fraud occurred.
D.
Both receipts require an application and the initial premium to be valid.
Question 19

A funeral home offers insurance to cover burial costs. The policy has a low premium and a face amount of $7,500. What type of policy is this, based on face amount?

A.
Variable universal life
B.
Industrial life insurance
C.
Ordinary whole life
D.
Adjustable term
Question 20

Monica purchases a whole life policy and chooses to pay her premium once a month. The insurer does not allow weekly or biweekly payments. What does this tell us about the type of policy Monica owns?

A.
It’s an ordinary life policy
B.
It’s an industrial life policy
C.
It’s a group term plan
D.
It’s a modified endowment
Question 21

Samantha, age 45, is diagnosed with a terminal illness and needs money to cover ongoing medical expenses. Instead of selling her policy to an investor, she chooses to access part of her policy’s death benefit directly from the insurance company while she is still alive. Which feature of her policy is Samantha using?

A.
Accelerated benefits provision
B.
Cash accumulation provision
C.
Human life value approach
D.
Key person insurance
Question 22

An employer and employee agree to share the cost of a permanent life insurance policy. The employer pays most of the premium, but the employee owns part of the cash value. What kind of arrangement is this?

A.
Group universal life
B.
Section 1035 exchange
C.
Deferred compensation
D.
Split dollar plan
Question 23

Which of the following is required before an HIV-related test can be administered during underwriting?

A.
Approval from the underwriter
B.
Written consent from the applicant
C.
Authorization from the MIB
D.
Notification of the applicant’s health provider
Question 24

An agent is explaining to a client how the insurer calculates life insurance premiums. She describes how age, health risk, and insurer costs are factored in. The client then asks, “Do your age or experience affect my premium?” What should the agent say?

A.
No, producer age is not used in premium calculations.
B.
Yes, experienced agents reduce your premium.
C.
Yes, agent age influences your costs.
D.
Yes, it’s part of the policy loading factor.
Question 25

After developing a serious illness, Jordan decides he wants permanent life coverage. His term policy includes a convertibility rider, so he switches to whole life without needing a medical exam. What feature did this rider protect?

A.
Coverage for final expenses
B.
Insurability regardless of health status
C.
A guaranteed payout
D.
Premium refund
Question 26

A bank requires life insurance for a borrower taking out a $50,000 car loan. If the borrower dies, the policy will pay the remaining loan balance. What kind of policy is this?

A.
Whole life insurance
B.
Deferred compensation plan
C.
Credit life insurance
D.
Group accidental death insurance
Question 27

After buying a family life insurance policy, Chris and Morgan have a baby. They’re surprised to learn the baby is already covered. Why is their newborn covered automatically?

A.
The policy includes an automatic child rider
B.
The child is only covered for 30 days after birth.
C.
The child has no health issue.
D.
They also bought a whole life policy when they purchased their health policy.
Question 28

Thomas has a whole life policy with a $250,000 face amount and $80,000 in cash value. His agent refers to the “amount at risk.” What is the amount at risk in Thomas's case?

A.
$170,000
B.
$250,000
C.
$80,000
D.
$330,000
Question 29

A married couple wants a single policy that helps with estate needs only after both of them have died. Which policy best fits this goal?

A.
Joint life (first-to-die) policy
B.
Family income policy
C.
Term policy with return of premium
D.
Survivor (second-to-die) life policy
Question 30

Universal life policies include a minimum guaranteed interest rate. What is the minimum guaranteed interest rate in a universal life policy?

A.
It is determined annually by the policyholder.
B.
It is set by the insurer and cannot decrease below this rate.
C.
It changes monthly based on market conditions.
D.
It applies only to the first year of the policy.
Question 31

David owns a variable life insurance policy but has grown concerned about market volatility. He’s thinking about adjusting his coverage to avoid investment risk. What option is typically available to him within the first two years of owning the policy?

A.
Switch to a fixed policy without new medical underwriting
B.
Cancel the policy and receive a full refund of premiums
C.
Apply for a new policy and complete a medical exam
D.
Forfeit any accumulated cash value in the account
Question 32

Cynthia is reviewing her variable life insurance policy and wants to understand where her investment funds are held. Her agent explains that these funds are kept in an account that’s not subject to the insurer’s creditors if the insurer becomes insolvent. What kind of account is Cynthia’s money held in, and what makes it different from the general account?

A.
It’s a separate account, where the insurer promises guaranteed investment returns
B.
It’s an internal portfolio of fixed annuities offered by the insurer
C.
It’s part of the insurer’s traditional reserves that fund general obligations
D.
It’s a separate account that is legally insulated from the insurer’s creditors
Question 33

What happens if an employee leaves a group life plan with a conversion privilege?

A.
They lose all coverage unless they reapply.
B.
They must undergo a medical exam to obtain new coverage.
C.
They can only obtain temporary insurance coverage after leaving the group.
D.
They may convert their coverage to an individual permanent policy without evidence of insurability.
Question 34

Several small businesses in the same industry want to provide group life coverage to employees but can’t meet the insurer’s size requirements individually. What type of arrangement can they form?

A.
A single employer trust
B.
A Multiple Employer Trust (MET)
C.
A pooled liability trust
D.
A union life group
Question 35

A parent gifts their 18-year-old child full rights to a juvenile life insurance policy. What type of assignment has occurred?

A.
A collateral assignment
B.
A non-cancellable assignment
C.
A relative assignment
D.
This is an absolute assignment
Question 36

A business owner assigns a life insurance policy to a lender while securing a business loan. What is the purpose of this collateral assignment?

A.
It makes the lender the new owner
B.
It transfers all rights to the lender permanently
C.
It guarantees that the insured receives the death benefit
D.
It temporarily gives the lender rights to the death benefit as loan collateral
Question 37

Denise buys a life policy but has second thoughts within a week. Which clause allows her to cancel the policy and receive a full refund?

A.
Free look provision
B.
Contestability clause
C.
Waiver of premium clause
D.
Grace period
Question 38

Monica is reading the insuring clause of her life insurance policy and wants to understand its purpose. What does this section typically include?

A.
The schedule of premium payments and frequency
B.
The list of riders and optional benefits
C.
The steps required to change the policy beneficiary
D.
The insurer’s promise to pay, the insured’s name, and the face amount
Question 39

Samantha dies by suicide three years after purchasing her life insurance policy. How will the insurer handle the claim?

A.
Pay the full death benefit to the beneficiary
B.
Deny the claim and refund premiums only
C.
Pay nothing because suicide is excluded
D.
Cancel the policy retroactively
Question 40

A life insurance applicant mistakenly lists the wrong age on their application. Years later, the insurer discovers the error after the insured passes. What will happen under the misstatement of age clause?

A.
The death benefit is voided entirely.
B.
The insurer sues the estate.
C.
The benefit is adjusted to reflect the correct age.
D.
The full benefit is paid with interest.
Question 41

Which of the following situations would most likely NOT be covered by an accidental death benefit rider?

A.
Death caused by a falling object
B.
Death due to a car accident
C.
Death while the insured was intoxicated
D.
Death due to a workplace injury
Question 42

Maria buys a cost of living rider. Why might this rider be especially valuable over time?

A.
It increases the face amount to keep pace with inflation.
B.
It reduces the policy’s premiums automatically.
C.
It prevents the insurer from ever increasing rates.
D.
It guarantees triple the death benefit at retirement.
Question 43

What is the accumulate at interest dividend option?

A.
The dividend is used to purchase additional insurance coverage.
B.
The dividend is applied to reduce future premiums.
C.
The dividend is left with the insurer to earn interest, which is taxable as ordinary income.
D.
The dividend is refunded to the policyholder in cash.
Question 44

Linda’s life insurance beneficiary chooses to receive $1,000 per month from the insurer until the full death benefit is paid out. What settlement option is being used?

A.
Cash settlement option
B.
Fixed amount option
C.
Interest-only option
D.
Fixed period option
Question 45

Derek decides to convert his deferred annuity into a lifetime income stream. After receiving his first monthly payment, he contacts the insurer asking to change the payout option and withdraw a large portion of the remaining balance. What will the insurer tell him?

A.
He can change the payout terms after six months
B.
He can access the remaining balance as a lump sum
C.
He can reverse the annuitization within 30 days
D.
He cannot withdraw funds or alter the payout terms once annuitization begins
Question 46

Olivia purchases a Single Premium Immediate Annuity (SPIA) with a lump sum and begins receiving income right away. What distinguishes a SPIA from other types of annuities?

A.
It requires monthly contributions.
B.
It has no accumulation phase.
C.
It begins payments immediately after purchase.
D.
It guarantees tax-free withdrawals.
Question 47

After retiring, Linda begins receiving monthly annuity payments. She is surprised that she no longer pays the 10% early withdrawal penalty, even though she is under age 59½. Why is this the case?

A.
Annuitized payments are treated as scheduled income streams, not withdrawals.
B.
The payments are considered tax-free once annuitization begins.
C.
The annuity becomes a life insurance contract at payout.
D.
The penalty is waived only for variable annuities.
Question 48

How is the tax liability on annuity payments determined after annuitization?

A.
Payments are taxed entirely as ordinary income.
B.
Payments are tax-free if the annuitant is over age 59½.
C.
Payments are taxed at the capital gains rate.
D.
Tax is based on the proportion of the payment attributable to growth.
Question 49

Ryan pays premiums on his individual life insurance policy. How are those payments treated under federal income tax law?

A.
They are deductible only if the policy is owned by a trust
B.
They are a deductible personal expense if itemized
C.
They are a personal expense and not tax-deductible
D.
They are a deductible medical expense
Question 50

Clara withdraws money from her annuity at age 50. What tax treatment will apply?

A.
The earnings are taxed as ordinary income and subject to a 10% penalty
B.
Only the principal portion is taxable
C.
The withdrawal is entirely tax-free if used for retirement
D.
The earnings are taxed as capital gains
Question 51

Anthony’s policy has grown in cash value, and he decides to fully surrender the contract. What tax risk does he face?

A.
Only premiums are taxed.
B.
Gains are taxed at favorable capital gains rates.
C.
The entire surrender value is tax-free.
D.
All gains above the basis are taxed as ordinary income.
Question 52

Lena has been working at her company for several years. Her employer has made contributions to her retirement plan. She asks if she will get to keep that money if she leaves the company. What is she asking about?

A.
Contribution limits
B.
Distribution penalties
C.
Vesting
D.
Beneficiary designation
Question 53

Alice works for a nonprofit hospital and contributes to a 403(b) plan. Her spouse works for the local government and contributes to a 457 plan. How do these plans compare to traditional corporate 401(k) plans?

A.
They are considered private-sector employer plans
B.
They have lower contribution limits than 401(k) plans
C.
They are both limited to after-tax contributions only
D.
They function similarly to 401(k) plans but are not corporate retirement plans.
Question 54

Which of the following is not considered a category of health insurance provider?

A.
Health Maintenance Organizations (HMOs)
B.
Blue Cross and Blue Shield
C.
Social Security investment funds
D.
Commercial insurers
Question 55

A self-employed individual applies for a non-ACA-compliant health insurance plan that uses full medical underwriting. Which factor will most significantly impact the premium offered?

A.
The applicant’s education level
B.
The applicant’s marital status
C.
The applicant’s medical condition and history
D.
The applicant’s occupation
Question 56

While reviewing her new health insurance policy, Ana notices a section labeled “Uniform Policy Provisions” that outlines requirements like the grace period and claim procedures. What is the primary purpose of these uniform policy provisions?

A.
To create consistency among policies and protect both parties
B.
To increase insurers' profits
C.
To allow insurers full control over claim decisions
D.
To make it harder for insureds to file claims
Question 57

Marta submitted proof of loss to her health insurer on January 1st. Her claim was denied, and she is considering legal action. Under the uniform Legal Action provision, what is the earliest and latest date she may file a lawsuit against the insurer?

A.
No earlier than March 1st and no later than January 1st two years later
B.
Any time within 90 days of the claim
C.
Any time after the date of claim denial, with no deadline
D.
Any time after January 15th, but no later than January 1st of the following year
Question 58

What does the Reinstatement provision require if a policy owner pays the reinstatement premium and the insurer does not respond within 45 days?

A.
The policy remains lapsed.
B.
The policy owner must reapply for coverage.
C.
The policy is automatically reinstated.
D.
The insurer must issue a new policy.
Question 59

An insured with a disability income policy becomes disabled and begins receiving monthly benefits. However, the insurer later finds that the insured’s pre-disability earnings were significantly lower than the benefit amount. What provision allows the insurer to reduce the benefit to align with actual earnings?

A.
Relation of Earnings to Insurance Provision
B.
Change of Occupation Provision
C.
Entire Contract Provision
D.
Benefit Adjustment Provision
Question 60

After receiving her new health insurance policy in the mail, Sofia reviews the terms and decides it’s not the right fit. A week later, she contacts the insurer to cancel it and asks for a full refund. Which provision gives her the right to do this?

A.
Free Look
B.
Conformity with State Statutes
C.
Insuring Clause
D.
Consideration Clause
Question 61

Maria recently enrolled in an HMO plan and wants to take advantage of the preventive services it offers. Which of the following services is she most likely able to receive without additional cost as part of her plan’s preventive care coverage?

A.
Out-of-network specialist consultation
B.
Prescription medication for chronic pain
C.
Emergency room treatment for a sprained ankle
D.
Annual physical exam and routine immunizations
Question 62

After reaching a certain limit in deductibles and coinsurance payments for covered medical expenses, Carlos is relieved to learn that his insurance will now cover 100% of any additional eligible costs for the rest of the year. Which provision in his Major Medical policy triggered this change?

A.
Preauthorization clause
B.
Stop-loss provision
C.
Corridor deductible
D.
Coordination of benefits
Question 63

After a car accident, a policyholder needs emergency dental surgery to repair broken teeth. Which of the following would NOT typically be excluded under a standard health insurance policy?

A.
Routine dental cleaning and X-rays
B.
Cosmetic teeth whitening
C.
Dental care required due to a covered accident
D.
Orthodontic treatment for crooked teeth
Question 64

While a patient is receiving inpatient hospital care, the insurance company contacts the attending physician to assess whether continued hospitalization is medically necessary. What type of utilization review is taking place?

A.
Prospective review
B.
Concurrent review
C.
Retrospective review
D.
External appeal
Question 65

John recently joined a company that provides group health insurance. Which of the following statements about group insurance is NOT true?

A.
Group plans provide coverage without requiring individual underwriting.
B.
Each employee can receive a Certificate of Coverage.
C.
The employer holds the master policy.
D.
Group health insurance is always more expensive than individual insurance.
Question 66

A group of small business owners forms a professional association to support industry standards and share resources. They now want to purchase group health insurance. Under typical rules, would they qualify?

A.
No, because the association must be formed solely for the purpose of getting insurance.
B.
Yes, if the association exists for a legitimate purpose beyond securing insurance.
C.
Yes, if the businesses have identical ownership and operate under a single tax ID.
D.
No, because only large corporations can qualify for group health insurance.
Question 67

Sarah is reviewing COBRA eligibility after several changes occurred in her company. Which of the following situations would NOT qualify an employee or dependent for COBRA continuation coverage?

A.
Employee termination
B.
Employee's death
C.
Employee's promotion
D.
Employee's voluntary resignation
Question 68

An insurance carrier receives an application from a local construction company with 10 full-time employees seeking group health coverage. Which federal law requires the insurer to offer coverage to this small employer group?

A.
ERISA
B.
HIPAA
C.
COBRA
D.
FMLA
Question 69

An employee had continuous group coverage for over a year, then switched jobs and enrolled in her new employer’s group plan 30 days later. What will the new plan do about coverage for her pre-existing condition?

A.
Delay coverage using a look-back period
B.
Impose a 3-month probationary period
C.
Require COBRA coverage from the old job
D.
Cover it immediately without any waiting period
Question 70

For a contributory group health plan, what minimum participation is typically required?

A.
At least 25%
B.
At least 50%
C.
At least 75%
D.
100%
Question 71

Tanya is receiving partial disability benefits after an injury that limits her to part-time work. Her insurer explains that these benefits are temporary and not meant for long-term income replacement. Based on typical policy terms, how long can partial disability benefits usually last?

A.
At least five years, regardless of her condition
B.
Until she reaches age 65
C.
Benefits are typically payable for less than 2 years.
D.
For the rest of her life if she continues to earn less
Question 72

Michael bought both a short-term and a long-term disability income policy. Which of the following statements about their coordination is NOT true?

A.
The short-term policy typically pays benefits for up to 6 months to 1 year.
B.
The long-term policy usually begins once short-term benefits end.
C.
Short-term and long-term policies always pay benefits at the same time.
D.
Long-term benefits may continue for 2 years, 5 years, or until age 65.
Question 73

Two partners own a graphic design firm. One of them becomes permanently disabled and can no longer contribute to the business. Which type of policy would provide the funds needed for the remaining partner to buy out the disabled partner’s share?

A.
Business Overhead Expense Policy
B.
Disability Buy-Out Policy
C.
Key Person Disability Insurance
D.
Group Disability Plan
Question 74

Which of the following benefits would typically be covered under a standard AD&D policy?

A.
Death due to a heart attack
B.
Death due to injuries sustained in a car accident while intoxicated
C.
Loss of vision in one eye caused by a pre-existing medical condition
D.
Loss of a leg below the knee in an accident
Question 75

Which of the following is NOT excluded under an AD&D policy?

A.
Loss sustained while committing a crime
B.
Loss caused while under the influence of alcohol or narcotics
C.
Loss caused by a workplace accident covered by workers’ compensation
D.
Loss of a hand above the wrist due to an accident
Question 76

A client is switching from one long-term care policy to another with no gap in coverage. Which of the following statements is true about how pre-existing conditions are treated in this replacement?

A.
The new policy cannot impose a new probationary period for pre-existing conditions.
B.
The free look period is reduced to 10 days for replacement policies.
C.
The client is required to complete a new medical exam before the policy is issued.
D.
The new policy must impose a new probationary period for pre-existing conditions.
Question 77

A family is reviewing a long-term care insurance policy for their mother, who was recently diagnosed with early-stage Alzheimer’s disease. Which of the following exclusions would not be allowed in a compliant LTC policy?

A.
Alzheimer’s disease
B.
Care received outside the United States
C.
Losses resulting from acts of war
D.
Treatment for pre-existing mental disorders
Question 78

Which statement about age and eligibility for LTC insurance benefits is TRUE?

A.
Benefits are available only after age 65
B.
Benefits require the insured to be eligible for Medicare
C.
There is no age requirement to receive LTC benefits if other eligibility criteria are met
D.
Applicants under age 50 are ineligible to receive LTC benefits
Question 79

On January 1, James began orthodontic treatment to correct a crossbite. Later that year, his dentist informs him that his dental insurance will no longer cover the remaining adjustments, even though the treatment is medically necessary. What is the most likely reason?

A.
The treatment is now considered cosmetic under the plan
B.
He reached the lifetime maximum benefit for orthodontic procedures
C.
His benefits renewed and now require a new deductible
D.
He reached the annual dollar maximum for preventive dental care
Question 80

Devon’s dental insurance plan covers routine exams and cleanings every six months. His insurer encourages him to use these benefits, even when he doesn’t have any current dental problems. What is the most likely reason this coverage is included?

A.
To increase premiums charged to policyholders
B.
To reduce claims for restorative procedures
C.
To allow more frequent dental visits
D.
To eliminate the need for comprehensive coverage
Question 81

Lena participates in her company’s Flexible Spending Account (FSA) program but forgets to use the remaining $600 in her account by the end of the plan year. Her employer does not offer a grace period or carryover option. What will happen to her unused FSA funds?

A.
They will roll over to the next year with interest
B.
They will be forfeited to the employer
C.
They will be refunded directly to Lena
D.
They will be transferred into a Health Savings Account (HSA)
Question 82

Which of the following is not part of OASDHI?

A.
TRICARE for active-duty military families
B.
Social Security retirement benefits
C.
Social Security disability income benefits
D.
Medicare medical expense coverage
Question 83

Carlos is reviewing Medicare eligibility for several clients at a community clinic. One is a 70-year-old retiree, another is a 58-year-old undergoing regular dialysis, and the third is a 60-year-old who recently retired early. Based on Medicare eligibility rules, which of the following individuals would qualify for Social Security medical expense reimbursement coverage?

A.
The 70-year-old retiree and the person on dialysis
B.
The person on dialysis
C.
The 70-year-old retiree
D.
The 60-year-old early retiree
Question 84

Maria enrolls in a Medicare Advantage (Part C) PPO plan that bundles her hospital and medical coverage and adds dental and vision benefits. Which statement correctly describes her situation?

A.
She no longer needs to pay the Part B premium.
B.
She must keep paying her Part B premium, plus any plan premium.
C.
She can drop Part A now that she has Part C.
D.
She should also buy a Medigap policy for cost-sharing.
Question 85

Which of the following statements about Medicare Part C is NOT true?

A.
It supplements Original Medicare by helping cover out-of-pocket costs.
B.
It combines coverage from both Medicare Part A and Part B.
C.
It may include benefits like dental, vision, or prescription drug coverage.
D.
It is also called a Medicare Advantage Plan.
Question 86

During a sales meeting, a producer tells a prospect, “I represent Medicare and can enroll you in an official government Medigap plan.” What’s the compliance issue?

A.
The statement is acceptable during Medigap open enrollment.
B.
It’s acceptable if the insurer offers Plan A.
C.
It’s prohibited—producers may not claim to represent Medicare or a government agency.
D.
It’s acceptable for direct-response sales only.
Question 87

A self-employed graphic designer buys an individual disability income insurance policy. When preparing her taxes, she asks whether she can deduct the premium. What is the correct explanation?

A.
These premiums qualify as medical expense deductions under IRS rules
B.
The IRS taxes disability benefits instead of allowing a premium deduction
C.
Disability income insurance is treated as life insurance for tax purposes
D.
Premiums are considered personal expenses and are not tax-deductible
Question 88

An employee is injured while performing regular job duties, and their claim for Workers’ Compensation is approved even though no negligence was found on the employer’s part. What principle allows this benefit to be paid?

A.
Coverage applies only to large employers with over 50 workers
B.
Benefits are only available for off-the-job injuries
C.
The system is based on liability without fault
D.
The employer must be found negligent before benefits are issued
Question 89

A Medigap policy is sold by mail (no producer). When must the Buyer’s Guide and Outline of Coverage be provided, and what is the minimum font size for the Outline?

A.
At application; 10-point type
B.
At the end of the free-look; 12-point type
C.
No later than the first premium draft; 14-point type
D.
No later than policy delivery; 12-point type
Question 90

Charles is enrolled in his company’s group disability income plan, and his employer pays 100% of the premium. He later becomes disabled and begins receiving monthly disability benefits under the policy. How are those benefits treated for tax purposes?

A.
They are tax-free
B.
They are deductible by the employee
C.
They are only taxable if the employee earns over $100,000 per year
D.
They are taxable as income to the employee
Question 91

Luca has an individual health insurance policy that he pays for entirely with after-tax dollars. Which of the following statements about the tax treatment of benefits from this policy is NOT true?

A.
Benefits are taxable only if Luca is self-employed
B.
Disability income benefits paid under an individual policy are tax-free if premiums were paid with after-tax dollars
C.
Health insurance benefits received from an individual policy are not taxable
D.
Benefits received from the policy are generally tax-free
Question 92

Carlos owns a marketing agency and provides group health insurance to his employees. His accountant wants to confirm how the premiums should be treated for tax purposes. How are the premiums paid by Carlos's business treated under tax law?

A.
Taxable to the employee
B.
Not tax-deductible for the employer
C.
Tax-deductible for the employer
D.
Tax-deductible only if the employee pays at least 50% of the premiums
Question 93

David owns a business with two partners and has set up a buy-sell agreement funded by life insurance. He’s reviewing the tax treatment of this arrangement with his financial advisor. Which of the following statements correctly describes how the policy is treated for tax purposes?

A.
The premiums are tax-deductible, and the benefits are tax-free
B.
Both premiums and benefits are tax-deductible
C.
Both premiums and benefits are taxable
D.
The premiums are not tax-deductible, but the benefits are tax-free
Question 94

After losing his job, Brian was offered COBRA coverage through his former employer’s group health plan. He decided to instead purchase an ACA plan through the Marketplace. Which of the following is an advantage of choosing an ACA plan over COBRA?

A.
ACA plans may be eligible for premium tax credits based on income.
B.
ACA plans do not cover preexisting conditions.
C.
ACA plans allow for indefinite coverage without premium payments.
D.
ACA plans do not meet minimum essential coverage requirements.
Question 95

Jasmine qualifies for a Special Enrollment Period (SEP) after moving to a new state. What is the timeframe she has to enroll in a Marketplace plan?
A.
7 days
B.
60 days
C.
30 days
D.
120 days
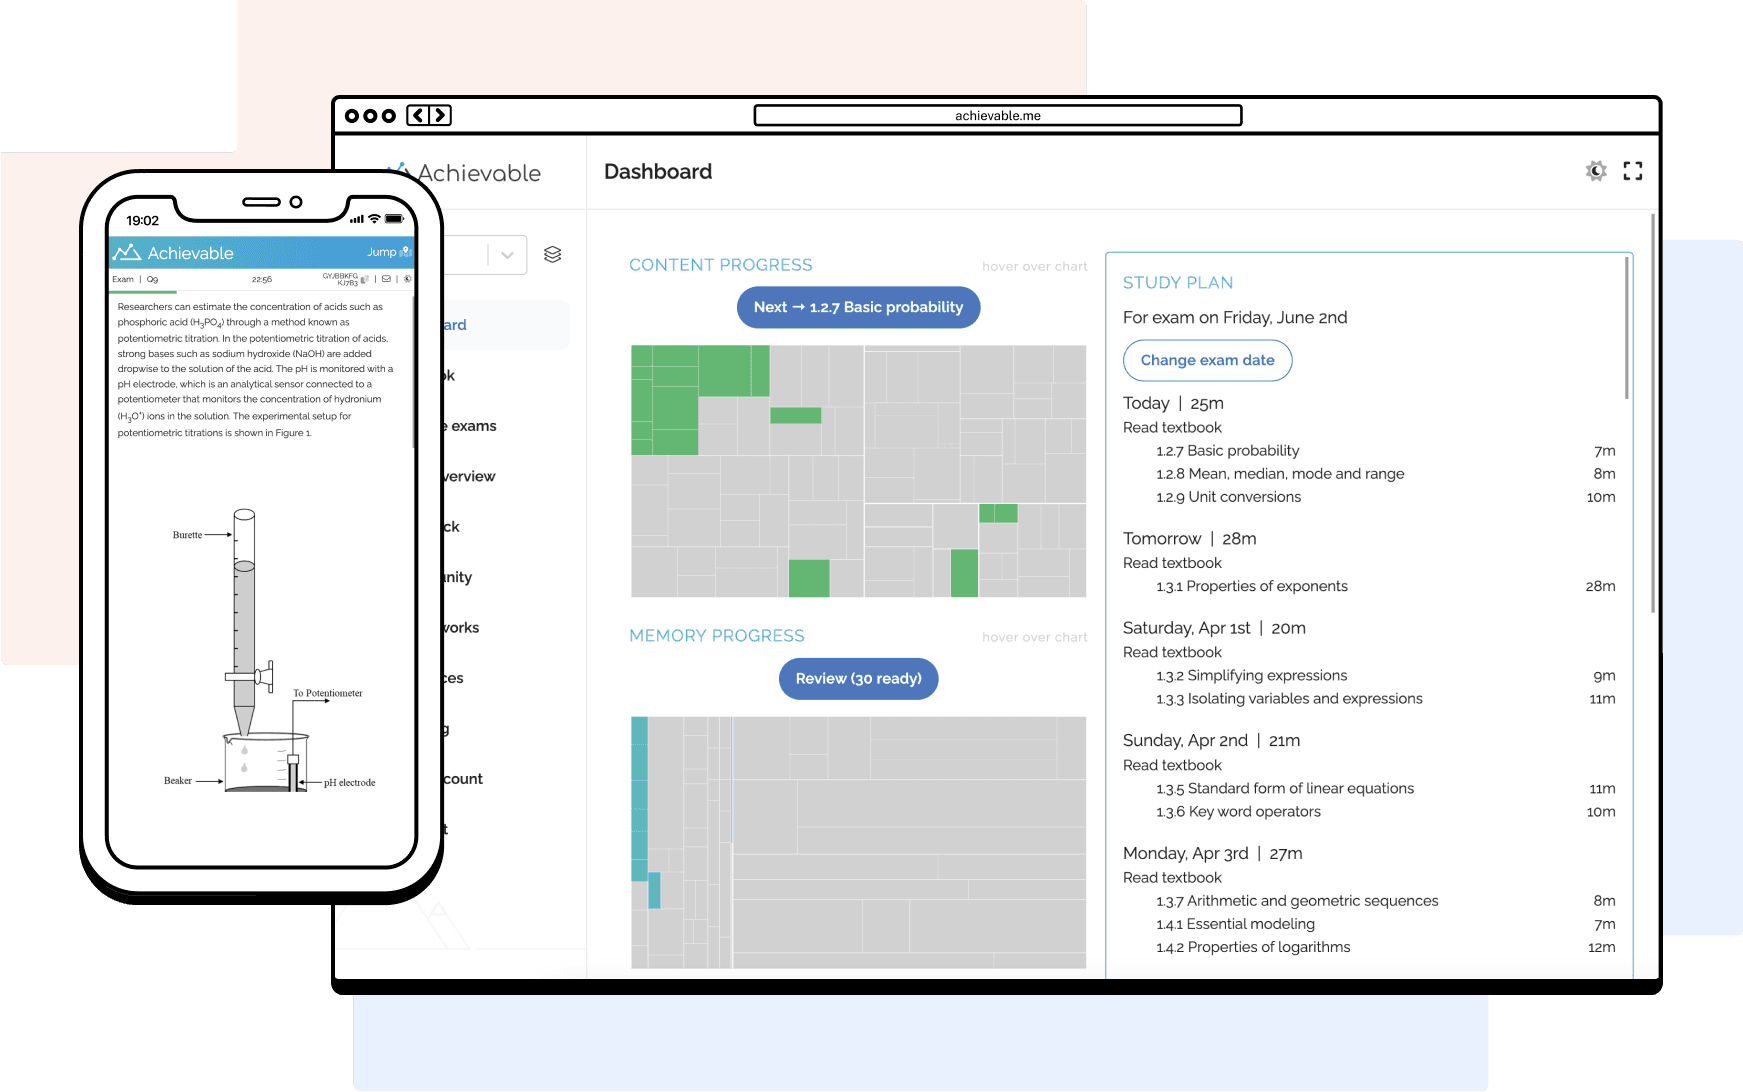
Achievable Life and Health Insurance dashboard
Pass the L&H insurance exam.
Guaranteed.
Achievable is the best online exam prep course: effective, personalized, and convenient. With Achievable, you'll spend less time studying and pass your exam the first time.