Life Insurance
study guide
Every chapter of the course summarized, with each section linked to its lesson.
Pass the first time
Try Achievable Life Insurance
No credit card required
This free Life Insurance study guide summarizes all 12 chapters of Achievable's Life Insurance course: what each covers, the points to remember, and its 25 sections in order. Read each chapter after you study it, or work through the whole guide before exam day.
Each section links to its full lesson in Achievable, with the review quizzes and full-length practice exams.
Chapter 1: General Insurance Concepts
6 sections
Free chapter
- Insurance basics: Insurance spreads financial risk across pooled premiums, insures pure risk, and uses avoidance, retention, reduction, and transfer as the four risk management methods.
- Core principles: Law of Large Numbers makes losses more predictable, indemnity restores pre-loss financial condition, insurable interest requires possible financial loss, and utmost good faith requires full disclosure.
- Policy structure and coverages: Declarations, insuring agreement, conditions, and exclusions make up the contract, while property, casualty, life, and accident & health insurance each cover their stated risks and provisions.
- Producers and risk transfer: Producers advise clients under state laws, insurance pools losses from many exposure units, and insurers use contract rules, insurable risk criteria, sources, authority, and regulation to manage claims.
In this chapter
Start this chapter free
Chapter 2: Producer Roles and Receipt Types
- Producer duties: Producers have a financial duty to collect and submit premiums under agency law, and the prudent person rule requires reasonable care to protect insurer and insured.
- Receipts and coverage: A binding receipt binds the insurer immediately, while a conditional receipt binds only if the applicant is later found insurable, and both require application plus initial premium.
- Delivery and premium rules: The producer must review the policy as applied for, explain any riders, exclusions, ratings, beneficiary, and free look period, and premiums must be held in fiduciary capacity and remitted promptly.
Study this chapter in Achievable
Chapter 3: Principles of Life Insurance
2 sections
- Life insurance types: Ordinary, Industrial, Group life, and Endowments are distinguished by target market, premium frequency, and payout structure, and Ordinary premiums are paid no more often than monthly.
- Policy features: Industrial life uses a debit agent and a 28 day grace period, Group life is often payroll deduction and typically no physical exam is required, and Endowments pay on death before a stated age or to the owner if they survive.
- Insurance applications: Life insurance replaces income and supports estate conservation and business continuation, while the human life value approach uses present value of future lost earnings and the needs approach is based on financial needs.
In this chapter
Study this chapter in Achievable
Chapter 4: Underwriting
- Underwriting basics: The goal is to accept acceptable risks, avoid insolvency, and maintain equity among risk classes by classifying applicants as standard, substandard, preferred, or uninsurable.
- Underwriting information: The application is the primary source and, with the authorization, supports access to medical records and MIB, while field underwriting requires accurate answers, proper signatures, and no erasures or white-out.
- Risk and premium rating: Life insurance answers are representations, and material misrepresentation or concealment may lead to rescission during the contestable period; substandard risks use flat extra premium, extra percentage premium, or rated-up age, and premium rates include mortality, expenses, and interest.
Study this chapter in Achievable
Chapter 5: Term Life Insurance
- Two insurance forms: Term insurance and permanent (whole life) insurance are the two main forms, and all life insurance products are variations or combinations of these two.
- Term insurance basics: Term insurance provides coverage for a limited period, has no cash value, expires with no payout if the insured survives the term, and starts with lower premiums that increase with age or renewal.
- Term policy features: Renewable term can renew without evidence of insurability, level premium term keeps face amount and premium constant, convertible term switches to whole life without medical exam, and decreasing term often covers declining debts.
Study this chapter in Achievable
Chapter 6: Whole Life Insurance
2 sections
- Amount at risk: Amount at risk equals insurer’s potential payout, and mortality charges increase with age while whole life uses cash value to offset rising costs and support level premiums.
- Policy varieties: Straight life, modified life, graded premium, limited pay, and single pay differ in premium timing and cash value growth, while combination policies blend term and whole life features.
- Flexibility and taxes: Joint life pays at the first insured's death, survivor life pays at the last, flexible premium policies adjust payments and benefits, and a MEC loses tax advantages.
Study this chapter in Achievable
Achievable Life Insurance
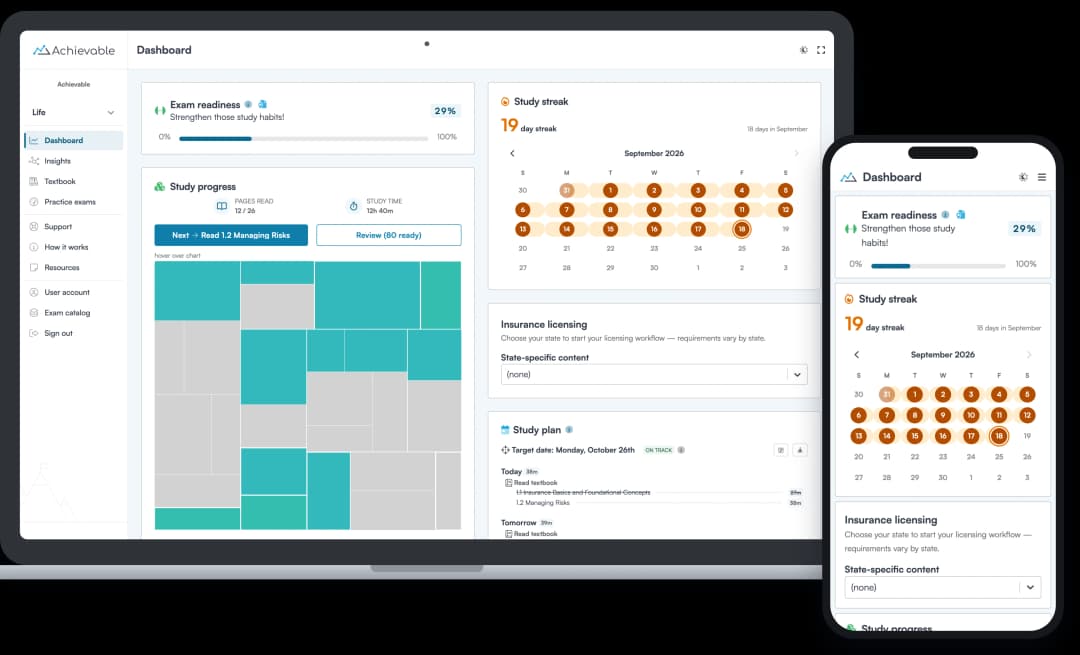
Pass the Life Insurance license exam on your first try with Achievable's interactive online license exam prep course. Includes everything you need: easy-to-understand online textbook, 920+ practice questions, and 5 full-length practice exams.
5 full-length practice exams for your state
920+ practice questions with explanations
State law questions for all 50 states and DC
Pass guaranteed, or your money back
Chapter 7: Variable Insurance Products
- Deflation helps fixed annuities: Deflation boosts a fixed annuity's purchasing power because a fixed income can buy more each year.
- Inflation erodes value: Inflation erodes the purchasing power of a fixed annuity unless the return outpaces inflation.
- Variable products hedge inflation: A variable insurance product provides a hedge against inflation while a fixed insurance product does not.
Study this chapter in Achievable
Chapter 8: Group Life Insurance
- Common applicants: Employers, Multiple Employer Trusts (METs), labor unions, and creditors may apply, and insurance must be incidental to the group’s main purpose.
- Policy and rates: One master policy covers multiple lives, participants receive certificates, and group rates depend on group characteristics and past claims history.
- Participation and conversion: Non-contributory plans require 100% participation, contributory plans 75%, and members may convert within 31 days without evidence of insurability.
Study this chapter in Achievable
Chapter 9: Life Insurance Provisions
5 sections
- Ownership rights: The owner controls policy decisions, can change beneficiary, take loans, surrender for cash value, and assign ownership, while the insured is the covered life and beneficiary receives proceeds.
- Assignment and beneficiaries: Absolute assignment is a full, irrevocable transfer, collateral assignment secures a loan, and beneficiary designations may be revocable, irrevocable, primary, contingent, or by class.
- Key clauses: The insuring, consideration, free look, entire contract, suicide, incontestable, misstatement of age, reinstatement, grace period, aviation, war, change of beneficiary, loan, and automatic premium loan provisions set policy rules.
- Riders and options: Riders add benefits for extra cost, and non-forfeiture, dividend, and settlement options determine how cash value, dividends, and proceeds are used if the policy lapses or pays out.
Study this chapter in Achievable
Chapter 10: Annuities
2 sections
- Annuity purpose: Annuities protect against outliving assets, guarantee payments for a fixed period or life, and grow tax-deferred without a contribution limit.
- Accumulation stage: Premiums may be paid as a lump sum or over time, withdrawals above cost basis are ordinary income, and a 10% penalty applies if the owner is under 59½ before annuitization.
- Payout rules: Annuitization is irreversible, payout options determine payment length and size, and fixed, variable, indexed, and market value adjusted annuities each follow specific tax and value rules.
In this chapter
Study this chapter in Achievable
Chapter 11: Taxation of Life Insurance Products
- Annuity taxation: Non-qualified annuity premiums are non-deductible and have no IRS contribution limit, cash growth is tax-deferred until withdrawn, and non-qualified withdrawals use LIFO while qualified withdrawals are fully taxable.
- Penalty and payments: Pre-59½ withdrawals face a 10% penalty on the taxable portion, with listed exceptions, and annuity payments are taxed proportionally with the exclusion ratio treating part of each payment as return of principal.
- Life policy taxation: Individual premiums are a personal expense, group term life excludes the first $50,000 from employee income, dividends are a return of excess premium, death benefits are generally excluded, and non-MECs use FIFO while MECs use LIFO.
Study this chapter in Achievable
Chapter 12: Qualified Retirement Plans
2 sections
- ERISA standards: ERISA sets standards for corporate retirement plans to qualify for tax benefits, focusing on vesting, eligibility, and nondiscrimination, and qualified plans allow employer contribution deductions.
- Vesting and plan rules: Employees are always 100% vested in their own contributions, while employer contributions use graded vesting or cliff vesting, and eligibility requires age 21 and service rules.
- Distributions and plans: Distributions are taxed as ordinary income and usually penalized before age 59½, while rollovers, nonqualified plans, and IRAs each follow specific rules for tax deferral and withdrawals.
Study this chapter in Achievable
More on the Life Insurance license exam
- Life Insurance license exam prep courseAchievable's course: online textbook, review quizzes and full-length practice exams.
- Life Insurance license exam format, content and scoringWhat's tested, how long it takes, what it costs, and the score you need to pass.
- Life Insurance FAQThe questions asked most about the exam and preparing for it, answered.
- Life Insurance study resourcesGuides and study advice from Achievable's instructors.
Pass the Life Insurance exam.
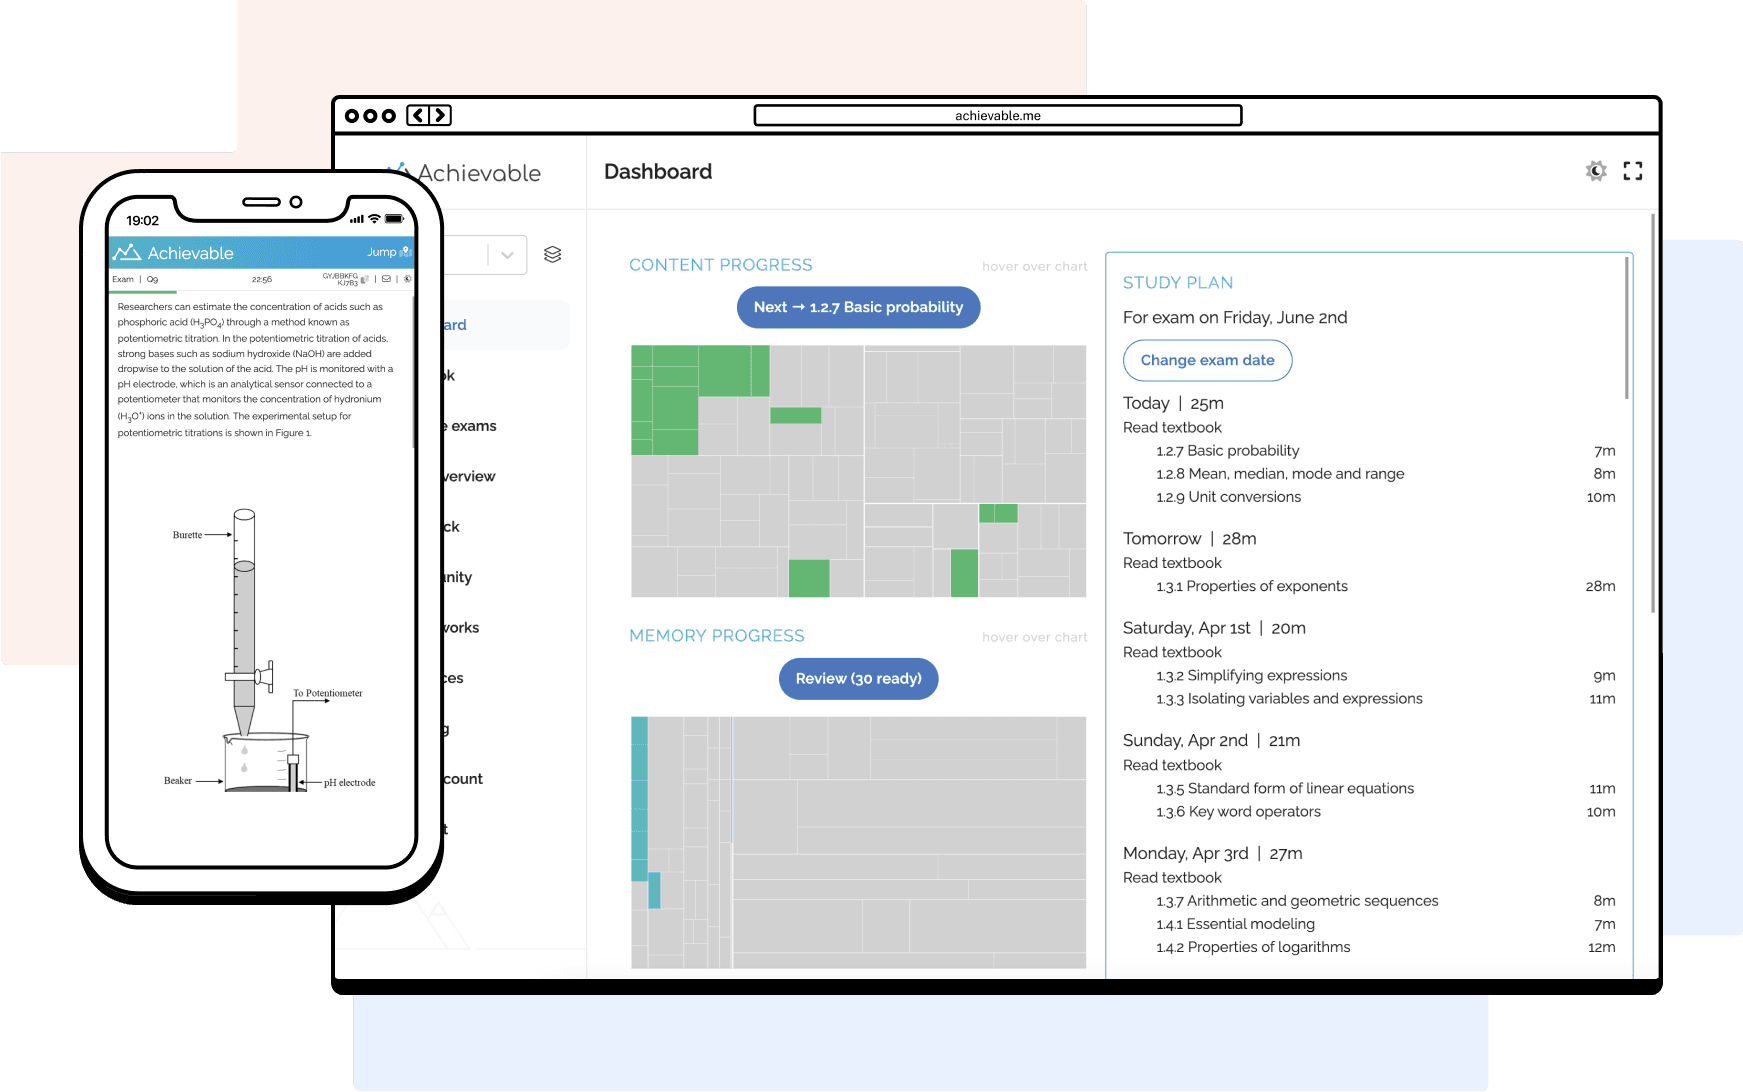
Guaranteed.Achievable is the best Life Insurance exam prep course: effective, personalized, and convenient. With Achievable, you'll spend less time studying and pass your exam the first time, or your money back.