Life & Health
study guide
Every chapter of the course summarized, with each section linked to its lesson.
Pass the first time
Try Achievable Life and Health Insurance
No credit card required
This free Life & Health study guide summarizes all 26 chapters of Achievable's Life & Health course: what each covers, the points to remember, and its 43 sections in order. Read each chapter after you study it, or work through the whole guide before exam day.
Each section links to its full lesson in Achievable, with the review quizzes and full-length practice exams.
Chapter 1: General Insurance Concepts
6 sections
Free chapter
- Insurance purpose: Insurance spreads financial risk through pooled premiums, allowing recovery from unexpected losses and promoting economic stability.
- Risk principles: Pure risk is insurable, speculative risk is not, and risk management uses avoidance, retention, reduction, and transfer.
- Core rules: Law of Large Numbers supports prediction, indemnity restores pre-loss condition, insurable interest is required, and utmost good faith demands honest disclosure.
- Contract and market: Declarations, insuring agreement, conditions, and exclusions shape coverage, while producers, insurers, and state regulation govern how policies are sold and administered.
In this chapter
Start this chapter free
Chapter 2: Producer Roles and Receipt Types
- Producer duties: Producers collect premiums and submit to insurer, act with prudent person rule, and fulfill fiduciary responsibility by managing client funds and acting in trust.
- Receipt types: A binding receipt binds the insurer to contract terms from the application date, while a conditional receipt binds only if the applicant is insurable.
- Receipt requirements: Both application and initial premium must be received for coverage during underwriting, and no initial premium means no coverage in force.
Study this chapter in Achievable
Chapter 3: Principles of Life Insurance
2 sections
- Life insurance types: Ordinary, Industrial, Group life, and Endowments are distinguished by premium frequency, target market, and policy structure.
- Personal and business uses: Life insurance meets financial needs at death and is also used for estate creation, cash accumulation, liquidity, estate conservation, buy-sell agreements, key person insurance, and Split dollar life insurance.
- Amount determination: The human life value approach uses present value of insured's lost future earnings until retirement, while the needs approach focuses on final expenses, housing, education, and retirement income supplement.
In this chapter
Study this chapter in Achievable
Chapter 4: Underwriting
- Underwriting basics: Insurers reject bad risks to avoid insolvency, and the underwriting department classifies applicants as standard, substandard, preferred, or uninsurable to maintain equity among risk classes and guard against adverse selection.
- Information and exams: The application is the primary source of underwriting information, and the applicant signs authorization for medical records and MIB access, with notice of insurance information practices by policy delivery.
- Ratings and premiums: Substandard risks may use flat extra premium, extra percentage premium, or rated-up age, while premiums reflect mortality, expenses (loading), and interest, with gross premium equal to net premium plus loading.
Study this chapter in Achievable
Chapter 5: Term Life Insurance
- Basic forms: Two main types of life insurance are term insurance and permanent (whole life) insurance, and all life insurance products are variations or combinations of these two.
- Term protection: Term insurance provides pure protection for a limited period with no cash value, lower initial premiums, and rising premiums with age or renewal for temporary or short-term needs.
- Term options: Renewable term, level premium term, convertible term, decreasing term insurance, and credit life insurance each add specific rules for renewal, conversion, benefit change, or debt coverage.
Study this chapter in Achievable
Chapter 6: Whole Life Insurance
2 sections
- Amount at risk: For whole life, amount at risk equals insurer’s potential payout, which is face amount minus cash value, and the mortality charge increases with age.
- Cash value and policies: Whole life accumulates tax-deferred cash value that begins by end of year 3, supports level premiums, and includes policy loans, illustrations, and types such as Straight Life, Limited Pay, and Single Pay.
- Flexible and group life: Joint life pays on first death, survivor life pays on last death, juvenile and flexible premium policies adjust coverage or payments, and a Modified Endowment Contract fails the seven pay test and loses tax benefits.
Study this chapter in Achievable
Chapter 7: Variable Insurance Products
- Licenses needed: Variable contracts are insurance products + securities, so an insurance license is required and a Series 6 or 7 investment license is also required.
- Account and risk: General account holds fixed product premiums/cash values and can be attached by insurer's creditors if insolvent, while separate account holds variable contract cash values, is not attachable, and variable contracts shift investment risk to the investor.
- Inflation and prospectus: Variable contracts tend to rise with inflation, fixed contracts can produce negative "real return" when inflation exceeds guaranteed rate, and a prospectus must be delivered at solicitation before premium is accepted.
Study this chapter in Achievable
Chapter 8: Group Life Insurance
- Applicants and purpose: Common applicants are employers, Multiple Employer Trusts (METs), labor unions, and creditors, and insurance must be incidental to group’s main purpose.
- Policy and underwriting: One master policy covers multiple lives, participants receive certificates as proof of coverage, and underwriting focuses on group characteristics with eligibility rules uniformly applied.
- Termination and conversion: Non-contributory plans require 100% employee participation and contributory plans require 75%, while members may convert coverage within 31 days with no evidence of insurability required.
Study this chapter in Achievable
Chapter 9: Life Insurance Provisions
5 sections
- Ownership rights: The owner controls the policy, can change the beneficiary, take loans, assign ownership, and a third party owner is not the insured.
- Assignment and beneficiaries: Absolute assignment is irrevocable and collateral assignment is temporary, while beneficiary designations may be revocable, irrevocable, primary, contingent, or by class.
- Core provisions: The insuring clause, consideration clause, free look, entire contract, suicide, incontestable, misstatement of age, reinstatement, grace period, aviation, war, change of beneficiary, policy loan, and APL clauses set policy rules.
- Riders and options: Riders add benefits for extra cost, and non-forfeiture, dividend, and settlement options determine how cash value, dividends, and proceeds are used or paid.
Study this chapter in Achievable
Chapter 10: Annuities
2 sections
- Annuity purpose: Annuities protect against outliving assets, guarantee payments for a fixed period or life, and grow tax-deferred even though premiums are not tax-deductible.
- Accumulation stage: The owner invests funds with no required premium schedule, withdrawals are taxable above cost basis and may trigger a 10% penalty under age 59½, and annuitization is irreversible.
- Payout rules: Life income, period certain, life with period certain, refund, joint life, and joint and survivor differ in payment length and size, while 1035 exchanges, equity indexed annuities, and MVA rules govern transfers and adjustments.
In this chapter
Study this chapter in Achievable
Chapter 11: Taxation of Life Insurance Products
- Annuity contributions: Non-qualified annuity contributions are not tax-deductible and have no IRS contribution limit, and all annuity growth is tax-deferred until withdrawn.
- Annuity distributions: Non-qualified annuities use the LIFO rule, qualified annuities are generally fully taxable, and withdrawals before age 59½ face a 10% IRS penalty plus ordinary income tax with listed exceptions.
- Life policy taxation: Individual policy premiums are not tax-deductible, life insurance death benefits are generally excluded from the beneficiary's gross income, and standard policies use FIFO while MEC policies use LIFO.
Study this chapter in Achievable
Chapter 12: Qualified Retirement Plans
2 sections
- ERISA standards: ERISA sets standards for corporate retirement plans to receive favorable tax treatment, and a qualified plan meets ERISA rules with employer contributions deductible as a business expense.
- Plan requirements: Vesting, eligibility, and discrimination rules control nonforfeitable rights, employee access limits, and nondiscrimination testing so benefits do not favor highly compensated employees.
- Distributions and plans: Distributions are taxed as ordinary income with a 10% early penalty before age 59½, while rollovers, nonqualified plans, and individual retirement plans follow separate rules.
Study this chapter in Achievable
Chapter 13: Health Insurance Basics
- Sources and types: Commercial insurers, service organizations, and government provide health insurance, and SSDI is a cash benefit, not health insurance; all listed types protect against financial loss from illness/injury.
- Underwriting factors: Age, gender, financial status, occupation, medical condition/history, and moral or morale hazards affect underwriting, and ACA medical expense plans must accept all applicants regardless of health status.
- Claims and vocabulary: Non-ACA substandard risks use exclusions, modification, or extra premiums, while claims follow the principle of indemnity and coordination of benefits so total payment is 100% or less of costs.
Study this chapter in Achievable
Achievable Life and Health Insurance
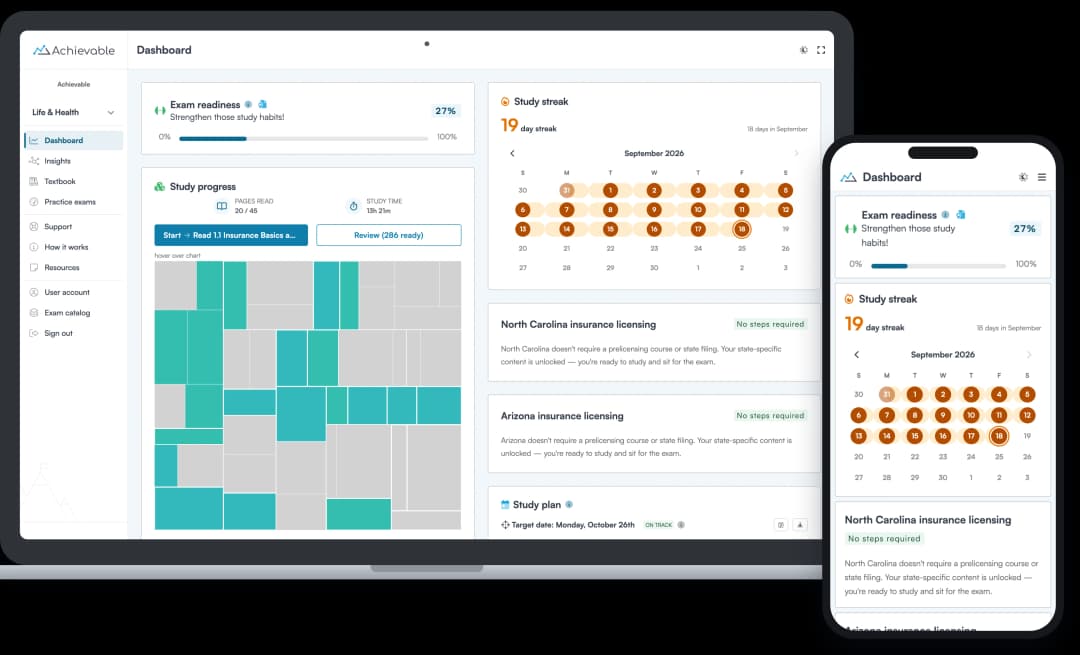
Pass the Life and Health Insurance license exam on your first try with Achievable's interactive online license exam prep course. Includes everything you need: easy-to-understand online textbook, 1,500+ practice questions, and 5 full-length practice exams.
5 full-length practice exams for your state
1,500+ practice questions with explanations
State law questions for all 50 states and DC
Pass guaranteed, or your money back
Chapter 14: Required Policy Provisions
- Required provisions: 12 required provisions protect the insured; 11 optional provisions protect the insurer, and insurer's wording changes must be as favorable to insured and approved by insurance director.
- Early policy rules: Minimum grace periods are 7 days (weekly), 10 days (monthly), and 31 days (other), the policy remains in force during grace period, and the owner can change beneficiary unless irrevocable beneficiary named.
- Claims and reinstatement: Written notice is required within 20 days of covered illness or injury, proof of loss within 90 days, claims are paid immediately on due written proof of loss, and reinstatement has a 45-day automatic rule and a 3-year application limit.
Study this chapter in Achievable
Chapter 15: Optional Policy Provisions
- Occupation and age: Change of occupation adjusts benefits/premiums for job risk changes, and misstatement of age makes benefits reflect correct age/premium.
- Overlapping coverage: Other insurance clauses limit payment when coverage exceeds a stated maximum or another insurer has not been told of the other coverage before the loss.
- Policy rules: Free look gives a 10-day (30-day for LTC/Medigap) full refund period, and cancellation, illegal occupation, and intoxicants and narcotics rules control refund and coverage.
Study this chapter in Achievable
Chapter 16: Medical Expense Insurance
2 sections
- Basic and major coverage: Basic medical expense insurance is first dollar coverage up to policy max, while major medical insurance has high maximum benefits, broad coverage, and cost-sharing features.
- Plan structures: Comprehensive major medical combines basic and major medical into one policy, HMOs use contracted providers and capitation, PPOs offer greater flexibility, and POS plans blend HMO and PPO features.
- Exclusions and controls: ACA-compliant medical expense insurance excludes custodial care, certain dental, vision, hearing aids, and other listed losses, while coordination of benefits and utilization management limit payment and review care.
In this chapter
Study this chapter in Achievable
Chapter 17: Group Health Insurance
2 sections
- Group insurance basics: A single master policy covers multiple people, is issued to the group sponsor, and is usually more affordable than individual coverage.
- Eligibility rules: Natural groups are formed for reasons other than insurance, fictitious groups are not eligible, and coverage often requires valid membership, probationary periods, and active-at-work status.
- Underwriting and continuation: Group underwriting rates the whole group, while HIPAA, COBRA, and conversion privilege set rules for pre-existing conditions, continuation, and switching to individual coverage.
In this chapter
Study this chapter in Achievable
Chapter 18: The Affordable Care Act (ACA)
- ACA purpose: The ACA expanded access to health insurance nationwide, added consumer protections, and standardized coverage rules and affordability.
- Core reforms: It bans preexisting condition exclusions and premium increases based on health, requires guaranteed issue and renewability, and sets dependent coverage to age 26.
- Coverage rules: Individual and small group plans must cover 10 essential health benefits, employer plans have a 90-day maximum waiting period, and employers with 50+ employees must offer affordable coverage.
Study this chapter in Achievable
Chapter 19: Disability Income Insurance
2 sections
- Income and waiting: Disability income insurance provides monthly income if unable to work due to sickness or injury, usually at less than 100% of gross income and best on net earned income; the elimination period is the waiting time before benefits start.
- Benefit definitions: The benefit period sets how long benefits are paid, and total disability may be defined as “any occupation” or “own occupation,” while partial, residual, recurrent, presumptive, and confining versus non-confining rules change when and how benefits are paid.
- Riders and uses: Optional riders can add guaranteed insurability, waiver of premium, Social Security, inflation protection, AD&D, rehabilitation, medical reimbursement, or return-of-premium features, and business policies may cover overhead, buyouts, key persons, or credit disability; exclusions include war, self-inflicted injuries, felony, and piloting personal aircraft.
Study this chapter in Achievable
Chapter 20: Accidental Death and Dismemberment Insurance
- AD&D basics: AD&D Insurance pays a lump-sum benefit only for accidental death or covered dismemberment, has no cash value, and is an inexpensive supplement or rider on health policies.
- Benefit amounts: The principal sum is the full benefit for death or severe loss, while the capital sum pays a percentage of the principal sum for lesser dismemberment.
- Coverage limits: Loss caused by committing or attempting a felony, intoxication, a narcotic not taken on a physician's advice, war, suicide, illness, or hazardous activities is excluded, and travel accident insurance covers only scheduled commercial flights.
Study this chapter in Achievable
Chapter 21: Long Term Care Insurance
- Policy basics: LTC policies pay a fixed dollar benefit for long-term/convalescent care, usually when the insured cannot perform at least 2 of 6 ADLs.
- Renewal protections: Individual LTC policies must be guaranteed renewable, cannot be canceled solely due to age or deteriorating mental/physical health, and may have a pre-existing condition probationary period of max 6 months.
- Coverage and terms: The Outline of Coverage must disclose premium increases, home health care cannot require prior facility/home/community care, and custodial care means help with ADLs rather than skilled medical treatment.
Study this chapter in Achievable
Chapter 22: Dental Insurance
- Group vs. individual: Dental insurance is primarily sold on group basis due to adverse selection, because individuals may delay treatment until insured.
- Benefit structure: Benefits are based on UCR charges, and charges above UCR, deductibles, and coinsurance are the insured’s responsibility, with integrated or separate deductibles and maximums.
- Policy types: Scheduled plans cover routine visits, cleanings, and preventive care, comprehensive plans add restorative and other services, and prepaid dental plans use capitation with full financial risk.
Study this chapter in Achievable
Chapter 23: Section 125 Plans and Limited Policies
- Cafeteria plans: Employer-established Section 125 plans allow pre-tax income for qualified expenses and reduce taxable income, mainly for health-related costs.
- Flexible spending accounts: An FSA uses pre-tax salary for health care or dependent care, but unused funds are forfeited at year-end under the "use it or lose it" rule.
- Health savings accounts: An HSA is available to those with high-deductible health plans, keeps funds with the individual, and rolls over unused funds tax-deferred.
Study this chapter in Achievable
Chapter 24: Federal Government Programs
2 sections
- Federal health benefits: Federal health insurance benefits include Disability Income Coverage and Medical Expense Reimbursement Coverage, and they are administered through Social Security (OASDI/OASDHI) and Medicare.
- OASDI and Medicare: OASDI is Old Age, Survivors, and Disability Insurance, OASDHI adds Health Insurance (Medicare), and Medicare has four parts: A, B, C, and D.
- Enrollment and military plans: Initial Enrollment Period is a 7-month window, late penalties apply to Part B and Part D, and TRICARE covers active military, retirees, families, and survivors not eligible for Medicare.
Study this chapter in Achievable
Chapter 25: Medigap and Medicaid
- Medigap basics: Medigap policies are sold and serviced by private insurers, are federally standardized by NAIC into 10 plans, and any insurer selling Medigap must offer Plan A.
- Sales requirements: A Buyer’s Guide and Outline of Coverage are required at application, replacing a policy needs Notice Regarding Replacement of Health Insurance, and all Medigap policies are guaranteed renewable with a minimum 30-day free look.
- Medicaid and workers’ comp: Medicaid is a state-administered, federally assisted welfare program for low-income/no-asset individuals, and workers' compensation covers injury or illness arising out of and during employment without fault.
Study this chapter in Achievable
Chapter 26: Health Insurance Taxation
- Individual premiums: Premiums are generally not tax deductible, except that medical expenses, including premiums, above 7.5% of AGI are deductible above that threshold.
- Disability benefits: Individually owned, after-tax premiums make benefits tax-free, while employer-paid or pre-tax premiums make benefits taxable.
- Business and group plans: Premiums for certain business policies are not deductible, business overhead expense insurance premiums are deductible, and group health insurance benefits are generally not taxed except disability income.
Study this chapter in Achievable
More on the Life & Health license exam
- Life & Health license exam prep courseAchievable's course: online textbook, review quizzes and full-length practice exams.
- Life & Health license exam format, content and scoringWhat's tested, how long it takes, what it costs, and the score you need to pass.
- Free Life & Health practice examPractice questions written to match the real thing, with an explanation for every answer.
- Life & Health FAQThe questions asked most about the exam and preparing for it, answered.
- Best Life & Health license exam prep coursesHow the leading providers compare on content, format and price.
- Life & Health study resourcesGuides and study advice from Achievable's instructors.
Pass the L&H insurance exam.
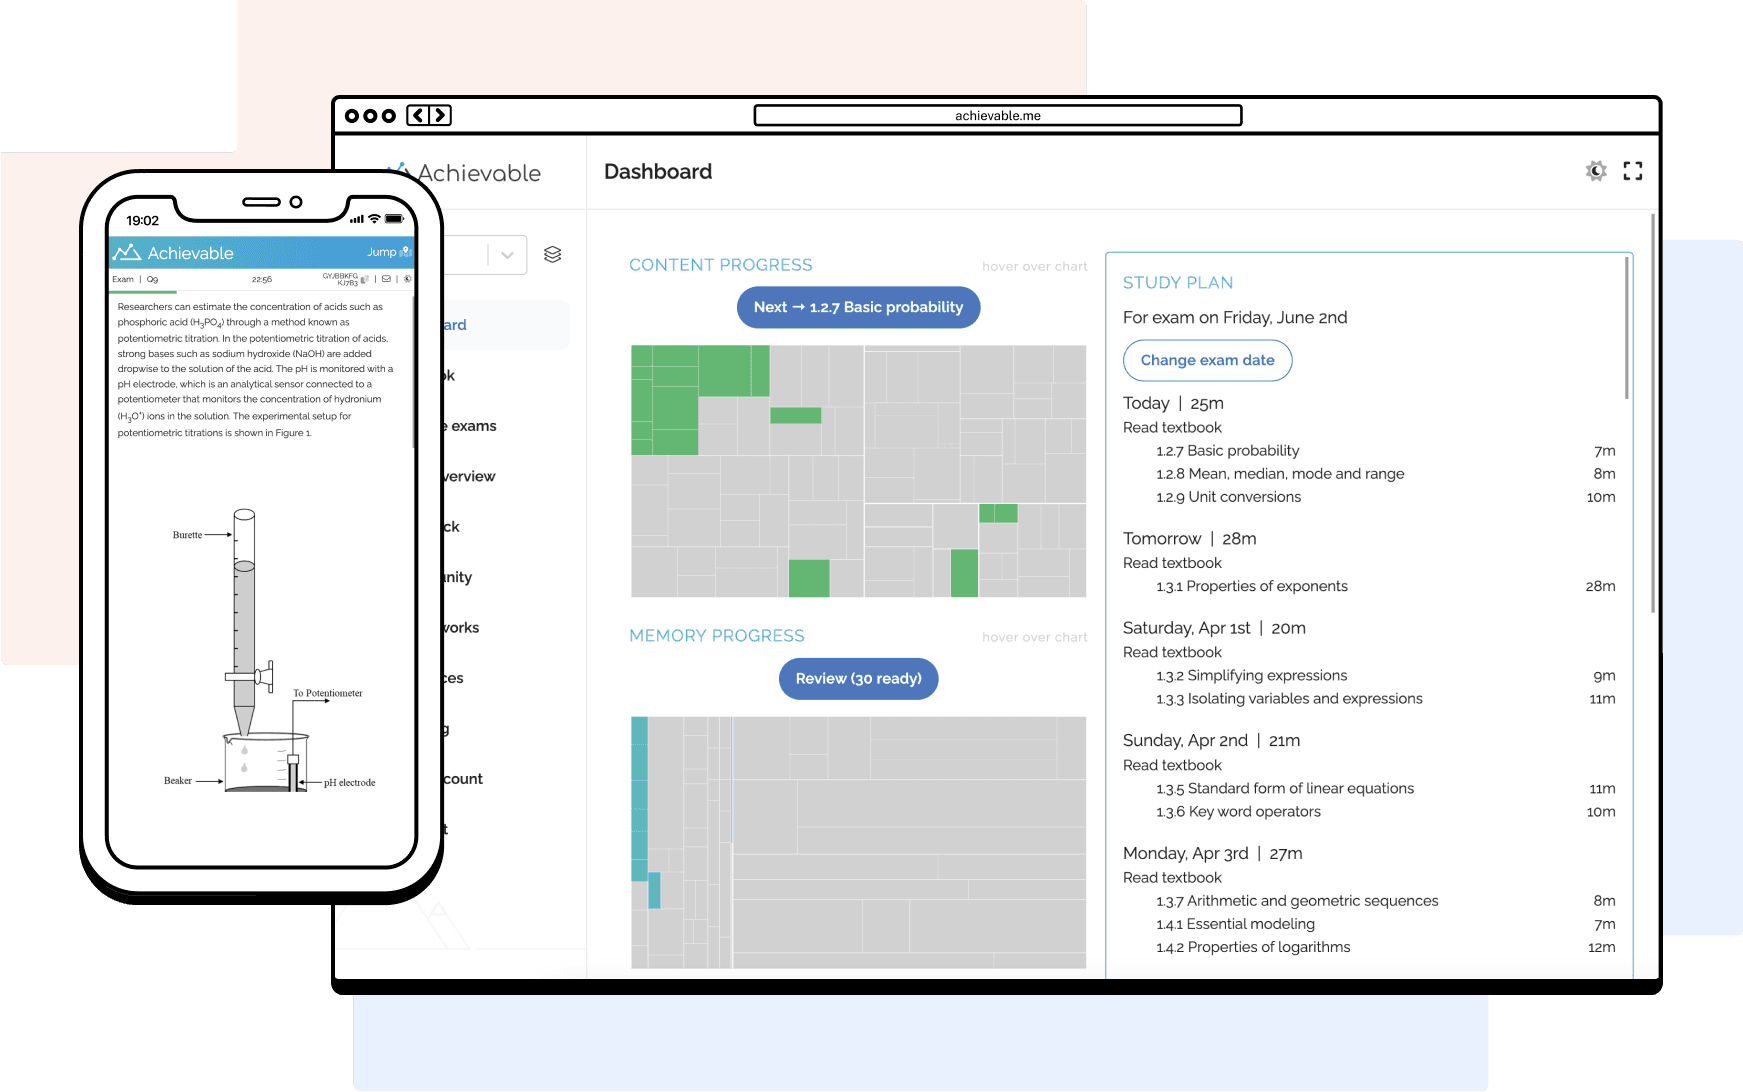
Guaranteed.Achievable is the best online exam prep course: effective, personalized, and convenient. With Achievable, you'll spend less time studying and pass your exam the first time.