Property & Casualty
study guide
Every chapter of the course summarized, with each section linked to its lesson.
Pass the first time
Try Achievable Property and Casualty Insurance
No credit card required
This free Property & Casualty study guide summarizes all 24 chapters of Achievable's Property & Casualty course: what each covers, the points to remember, and its 30 sections in order. Read each chapter after you study it, or work through the whole guide before exam day.
Each section links to its full lesson in Achievable, with the review quizzes and full-length practice exams.
Chapter 1: General Insurance Concepts
7 sections
Free chapter
- Insurance purpose: Insurance spreads financial risk across policyholders via pooled premiums and helps predict losses, financial stability, and recovery from unexpected events.
- Risk principles: Risk is uncertainty of loss, pure risk is insurable, speculative risk is not insurable, and insurance is the main transfer tool in four management methods.
- Core contract rules: Law of Large Numbers, indemnity, insurable interest, and utmost good faith govern insurance, while declarations, insuring agreement, conditions, and exclusions structure the contract.
- Property and casualty: Property insurance covers physical property damage or loss, casualty insurance centers on liability for injury or damage to others, and negligence requires duty, breach, injury/damage, causation.
- Life, health, and producers: Term, permanent, group life, accident & health, and group health each use specific coverage and cost-sharing features, and producers must advise clients and follow state laws and ethical standards.
Start this chapter free
Chapter 2: P&C Insurance Basics
- Loss and cause: Direct loss is actual physical damage from a covered peril, and indirect/resultant loss stems from a direct loss.
- Indemnity rules: P&C policies are contracts of indemnity, insurable interest must exist at application for life insurance and at time of loss for property insurance, and ACV is replacement cost minus depreciation.
- Liability and administration: Liability coverage protects against legal responsibility for bodily injury or property damage to others, and key administration concepts include pro rata, primary and excess, contributory negligence, comparative negligence, cancellation, vacancy, appraisal, assignment, and salvage.
Study this chapter in Achievable
Chapter 3: Underwriting
- Underwriting basics: Insurers accept risk, but not every applicant, and too many poor risks can cause insolvency, so the underwriting department reviews applications for acceptability.
- Risk selection goals: Underwriting seeks equity among risk classes, matches premiums to risk, and allows risk-based discrimination into standard, substandard, preferred, and uninsurable while prohibiting unfair discrimination.
- Key information sources: The application is the most important source of underwriting info, supported by the producer's report, inspections, consumer reports, financial ratings, and waiver and estoppel.
Study this chapter in Achievable
Chapter 4: Claims Settlement
- Claim settlement basics: Policies pay up to stated limits, and a payable claim requires written proof of loss before a commercial property insurer pays within 30 days once the amount is agreed or appraised.
- Valuation methods: Market value, valued policy, agreed value, stated amount, and functional replacement cost each use a different payout basis, while ACV prevents profiting and replacement cost pays like kind and quality without depreciation.
- Coinsurance and deductibles: Coinsurance requires insurance at or above the specified percentage, reduces underinsured payments proportionally, and deductibles apply per occurrence so each separate loss has its own deductible.
Study this chapter in Achievable
Chapter 5: Dwelling Policies (DP)
- Eligibility and forms: Dwelling forms are monoline policies for residential property, owner- or non-owner-occupied, including under construction; farms, 5+ unit structures, and commercial/business use structures are ineligible, and mobile homes require permanent affixation to a foundation plus endorsement.
- Coverage forms: Dwelling '02 program has DP1 (Basic), DP2 (Broad), and DP3 (Special); WHARVVES is automatic in DP2/DP3, DP1 only by add-on, and DP3 is all-risk/open-peril for Coverage A and B.
- Property and liability: Coverage A, B, C, D, and E apply with stated limits and exclusions, and the personal liability supplement adds Coverage L and Coverage M with named insured, resident spouse, resident relatives, and residents under 21 in care.
Study this chapter in Achievable
Chapter 6: Dwelling Policy Conditions
- Other coverages: All dwelling forms include Other Coverage extensions, subject to deductible except Fire Department Service Charge, and some reduce existing limits while others are additional insurance.
- Core protections: DP-1 has 8 extensions, while DP-2/DP-3 share those 8 plus 4 more, including VMM as a covered peril and key policy conditions like appraisal, loss settlement, and cancellation.
- Endorsements and terms: Endorsements can add coverage or change terms, and key vocabulary includes Appurtenant, Deductible, Conditions, Endorsement, Pair or Set, and Removal.
Study this chapter in Achievable
Chapter 7: Home Owners Policies (HO)
- Policy structure: Homeowners insurance is a multi-line package with property coverage in Section I and personal liability in Section II, based on ISO 2011 edition forms.
- Eligibility and forms: It must insure a residence with a personal stake, and HO-2, HO-3, HO-5, and HO-8 are for owner-occupants of 1–4 family dwellings only, while HO-4 and HO-6 fit tenants and condo or co-op unit owners.
- Core coverages: Coverage A, B, C, and D and the Section II coverages use stated limits, named-peril or open-perils rules, and key exclusions that differ by form, especially HO-5, HO-6, and HO-8.
Study this chapter in Achievable
Chapter 8: Homeowners Policy Definitions and Conditions
- Basic definitions: “You”/“your” means the named insured plus resident spouse, and “insured” includes resident relatives, certain residents under 21, and eligible full-time students.
- Property and loss rules: “Residence premises,” “insured location,” “bodily injury,” “property damage,” “occurrence,” and “business” are defined, and personal property pays actual cash value while buildings use the 80% replacement cost rule.
- Conditions and deadlines: Duties after loss, appraisal, other insurance, suit, payment, mortgagee, cancellation, nonrenewal, assignment, subrogation, and fraud all follow strict notice and timing rules, with Section I fraud voiding coverage for all insureds and Section II fraud affecting only that insured.
Study this chapter in Achievable
Chapter 9: Endorsements and Scheduled Property
- Inflation and value: Inflation guard auto-increases Coverage A/B/C/D limits yearly by set %, and personal property replacement cost pays replacement cost with no depreciation deduction.
- Occupancy endorsements: Business pursuits extends liability for an insured employee's eligible occupations away from residence, permitted incidental occupancies removes the business-activity exclusion, and home day care extends liability by headcount.
- Property and liability coverage: Mobile homes, watercraft, unit owners coverage, water back-up/sump overflow, personal injury, earthquake, scheduled personal property, and personal articles floater each add specific coverage, limits, or independence.
Study this chapter in Achievable
Chapter 10: Personal Auto Insurance (PAP)
- PAP basics: Personal Auto Policy (PAP) is a package policy combining property, liability, and injury coverage in the Coverage Territory of the US, its possessions, Puerto Rico, and Canada.
- Defined terms and liability: Bodily Injury includes death, and Part A pays damages the insured is legally responsible for, with split limits, supplementary payments, and out-of-state coverage.
- Other coverages and rules: Parts B through F add medical payments, uninsured/underinsured motorist coverage, collision and comprehensive, duties after loss, and general provisions on cancellation, fraud, and subrogation.
Study this chapter in Achievable
Chapter 11: Flood and Other Limited Policies
- NFIP basics: FEMA administers NFIP because flood is excluded from standard property policies, and participating communities need FEMA-approved floodplain ordinances or coverage is unavailable.
- Flood coverage rules: SFIP covers direct physical loss from flood, including mudflow, but excludes landslides, earth movement, sewers or drains unless flood is the proximate cause, and many listed properties.
- Other limited policies: Mobile home, earthquake, inland marine, CPL, and umbrella policies add special coverages and exclusions, with earthquake using a percentage deductible and umbrella broadening coverage beyond underlying policies.
Study this chapter in Achievable
Chapter 12: Commercial Package Policy (CPP)
- Policy purpose and definition: A CPP combines multiple coverages into one policy, one insurer, single policy period, common declarations, and common conditions, and 2 or more coverage parts makes a package policy.
- Coverages and extensions: Available parts include liability, commercial property, inland marine, crime, auto, equipment breakdown, and farms, and coverage extensions are additional insurance limited by amount or time.
- Forms and exclusions: Each coverage form has its own insuring agreement and exclusions are found in the causes of loss form, while Commercial Property means property insurance for commercial ventures.
Study this chapter in Achievable
Achievable Property and Casualty Insurance
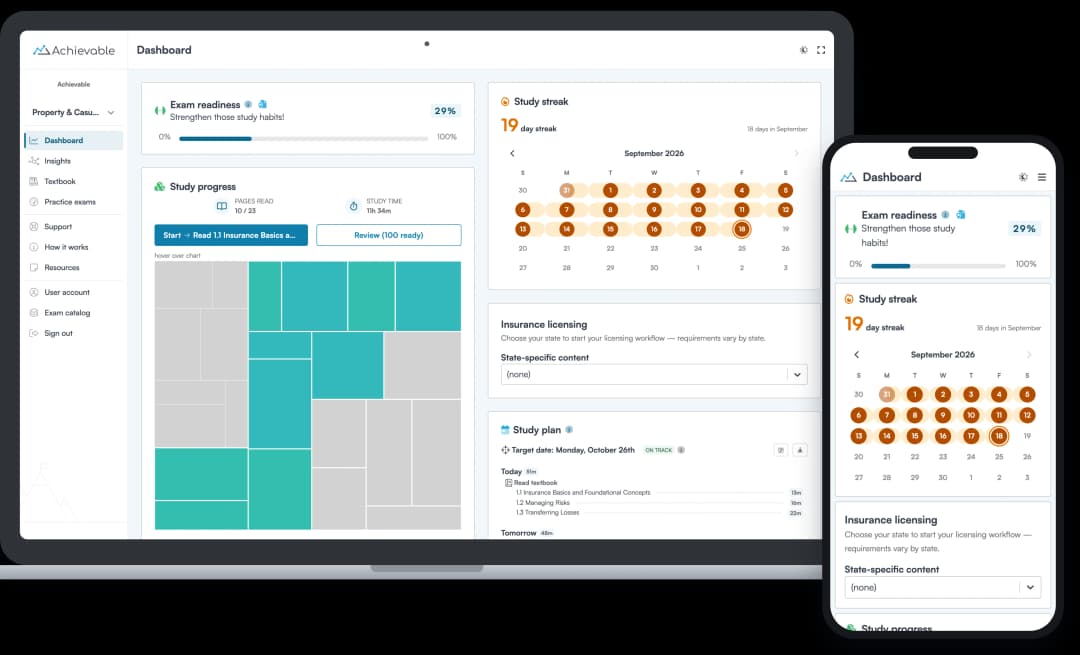
Pass the Property and Casualty Insurance license exam on your first try with Achievable's interactive online license exam prep course. Includes everything you need: easy-to-understand online textbook, 1,300+ practice questions, and 5 full-length practice exams.
5 full-length practice exams for your state
1,300+ practice questions, explained in depth
State law questions for all 50 states and DC
Pass guaranteed, or your money back
Chapter 13: Commercial Property Forms
- Commercial forms: Commercial property forms insure buildings, contents, and dependent income, including Building and Personal Property, Builders Risk, Business Income, Legal Liability, Extra Expense, Condominium Association, and Condominium Commercial Unit Owners.
- Building coverage: The Building and Personal Property Coverage Form covers building, your business personal property, and personal property of others only when declarations show a limit for that property type.
- Key rules: Additional coverages, limits, valuation, optional coverages, Builders Risk, Business Income, Extended Business Income, Legal Liability, and Extra Expense each follow their stated caps, periods, conditions, and exclusions.
Study this chapter in Achievable
Chapter 14: Cause of Loss Forms and Commercial Property Endorsements
- Cause of loss forms: Coverage form = what property is covered; cause of loss form = what perils are covered, and Basic and Broad are named perils while Special is open perils.
- Key endorsements: Ordinance or law, spoilage, peak season limit of insurance, value reporting form, and earthquake endorsement modify property coverage to fit business needs.
- Important rules: Basic and Broad, only Special covers theft with set limits, spoilage covers breakdown/contamination and power outage, and value reporting form under-reporting pays only proportion reported/actual.
Study this chapter in Achievable
Chapter 15: Commercial Crime Insurance
- Coverage gaps: Commercial property insurance leaves gaps because the BPP form excludes money, securities, notes, basic/broad cause of loss forms don't cover theft, and the special form excludes employee dishonesty and property surrendered by trick.
- Insuring agreements: Seven agreements apply only if a limit is shown in declarations, and money/securities are covered for theft, disappearance, or destruction while other property is covered only for robbery and safe burglary if inside premises.
- Loss and conditions: Loss sustained form requires the occurrence during the policy period, discovery form requires discovery during the policy period, and duties after loss include notice ASAP and sworn proof of loss within 120 days.
Study this chapter in Achievable
Chapter 16: Commercial General Liability (CGL)
- CGL triggers: Businesses face liability from property ownership, operations, manufacturing, completed work, and contracts, and occurrence covers events during the policy period while claims-made is triggered by the claim date after any retroactive date shown.
- Core coverages: Coverage A applies to bodily injury/property damage from an occurrence, Coverage B covers personal and advertising injury offenses, and Coverage C pays no-fault medical payments if reported within 1 year of the accident.
- Policy rules: Bankruptcy does not void payment duty, CGL is usually primary, the General Aggregate Limit excludes products-completed ops, and the policy territory includes the USA/territories, Puerto Rico, Canada, international waters/airspace, and worldwide for products sold or made in covered territory.
Study this chapter in Achievable
Chapter 17: Commercial Auto Insurance
- Commercial auto basics: Commercial Auto Coverage Part is added to CPP to cover BI/PD from ownership, maintenance, or use of covered autos, and it is similar to PAP but for business exposures.
- Policy structure and coverage: The Business Auto Coverage Form has five sections, covered-auto symbols on the declarations page determine which autos are insured, and Section II and Section III provide liability and physical damage coverage with stated exclusions and options.
- Special forms and rules: Garage Coverage, Garage keepers' Liability, and Truckers' Coverage apply to their specific operations, and the Motor Carrier Act of 1980 requires proof of liability insurance with MCS-90 endorsement and minimums of $750,000, $5 million, or $1 million.
Study this chapter in Achievable
Chapter 18: Ocean and Inland Marine Insurance
- Ocean marine coverage: Ocean marine insurance covers ships and cargo on oceans and navigable waters, with hull, cargo, freight, and protection & indemnity (P&I) risks.
- Marine rules: Hull policies name perils, cargo policies use named perils or "all risks," and key implied warranties are seaworthiness, condition of cargo, legality, and no deviation in voyage.
- Inland and aviation: Inland marine insures movable or business property, including transit, floaters, bailee custody, and specialized forms, while aviation insurance covers aircraft hull, aircraft liability, and hangar keeper's liability.
Study this chapter in Achievable
Chapter 19: Equipment Breakdown and Farm Coverage
- Equipment breakdown coverage: Formerly boiler and machinery insurance, it covers breakdown of boilers, pressure vessels, and mechanical/electrical machinery, and is added to CPP or optional under businessowners policy.
- Coverage trigger and benefits: Property forms exclude mechanical breakdown, artificially generated electrical energy/arcing, and explosion of steam boilers/pipes/engines/turbines, but equipment breakdown covers direct damage, expediting expenses, business income, spoilage damage, and related coverages.
- Farm coverage basics: Farm coverage combines personal and commercial protection with ten coverages A–J, and its property and liability forms apply only when the limit is shown in declarations.
Study this chapter in Achievable
Chapter 20: Professional Liability
- Professional liability: Specialized liability coverage for professionals covers liability from negligence, and several common forms exist, tailored by profession.
- Malpractice coverage: Malpractice insurance covers physicians, surgeons, dentists, hospitals, and protects against claims from third-party injury due to insured's negligence.
- E&O and D&O: Errors and Omissions covers alleged negligence in professional duties, and Directors and Officers protects against lawsuits from stockholders or others alleging mismanagement.
Study this chapter in Achievable
Chapter 21: Business Owners Policy (BOP)
- BOP overview: BOP is the commercial equivalent of homeowners policy and combines property and liability coverage for small/medium businesses in one simplified package.
- Section I coverage: Section I uses open-peril property coverage for covered property at described premises, and business income and extra expense are additional coverages paid outside Section I limits.
- Key conditions: Replacement cost applies if limit ≥80% of replacement cost, and vacancy >60 consecutive days triggers special provisions with some losses excluded and others reduced by 15%.
Study this chapter in Achievable
Chapter 22: Businessowners Policy: Section II Liability
- Section II overview: It covers legal liability from business premises ownership and business activities, and liability insurance pays third parties for injury or damage the insured is responsible for.
- Business liability coverage: It pays damages for bodily injury, property damage, and personal/advertising injury, with defense, supplementary payments, and listed exclusions applying as stated.
- Medical and limits: Medical expenses are paid regardless of fault, and the chapter also defines who is an insured, the limits of insurance, and the general conditions for Section II.
Study this chapter in Achievable
Chapter 23: Workers Compensation Insurance
- Basic rules: Workers Compensation is a no-fault system where negligence is irrelevant, injury can't be self-inflicted, and the employer pays full cost for only work-related injuries/sickness.
- Policy benefits: Part I mandates Medical Expense, Income Benefits, Dependent Funeral Benefit, and Vocational Rehabilitation, while Part II is Employers Liability and Part III is optional Other States coverage.
- Premiums and laws: Premiums use rate × payroll/remuneration per classification, Experience Modification Factor shows claim history, and special federal laws include Longshore, Jones, FECA, and FELA.
Study this chapter in Achievable
Chapter 24: Bonding
- Suretyship basics: Suretyship is a three-party agreement, unlike insurance's two parties, and bonding ensures guaranteed performance while the surety protects the obligee if the principal fails.
- Bond types: Fidelity bonds protect employers from dishonest employees, while surety bonds guarantee performance of acts, including contract bonds, judicial bonds, license and permit bonds, and public official bonds.
- Bond terms: Surety bonds remain until canceled or performance completed, and the surety can recover paid damages from the principal.
Study this chapter in Achievable
Property & Casualty license exam at a glance
- Questions
- 100-150 multiple-choice questions
- Time
- 2-4 hours (varies by state)
- Passing score
- 70%
- Exam fee
- $40-$150 (varies by state)
More on the Property & Casualty license exam
- Property & Casualty license exam prep courseAchievable's course: online textbook, review quizzes and full-length practice exams.
- Property & Casualty license exam format, content and scoringWhat's tested, how long it takes, what it costs, and the score you need to pass.
- Free Property & Casualty practice examPractice questions written to match the real thing, with an explanation for every answer.
- Property & Casualty FAQThe questions asked most about the exam and preparing for it, answered.
- Best Property & Casualty license exam prep coursesHow the leading providers compare on content, format and price.
- Property & Casualty study resourcesGuides and study advice from Achievable's instructors.
Pass the P&C insurance exam.
Guaranteed.Achievable is the best Property and Casualty Insurance exam prep course: effective, personalized, and convenient. With Achievable, you'll spend less time studying and pass your exam the first time, or your money back.